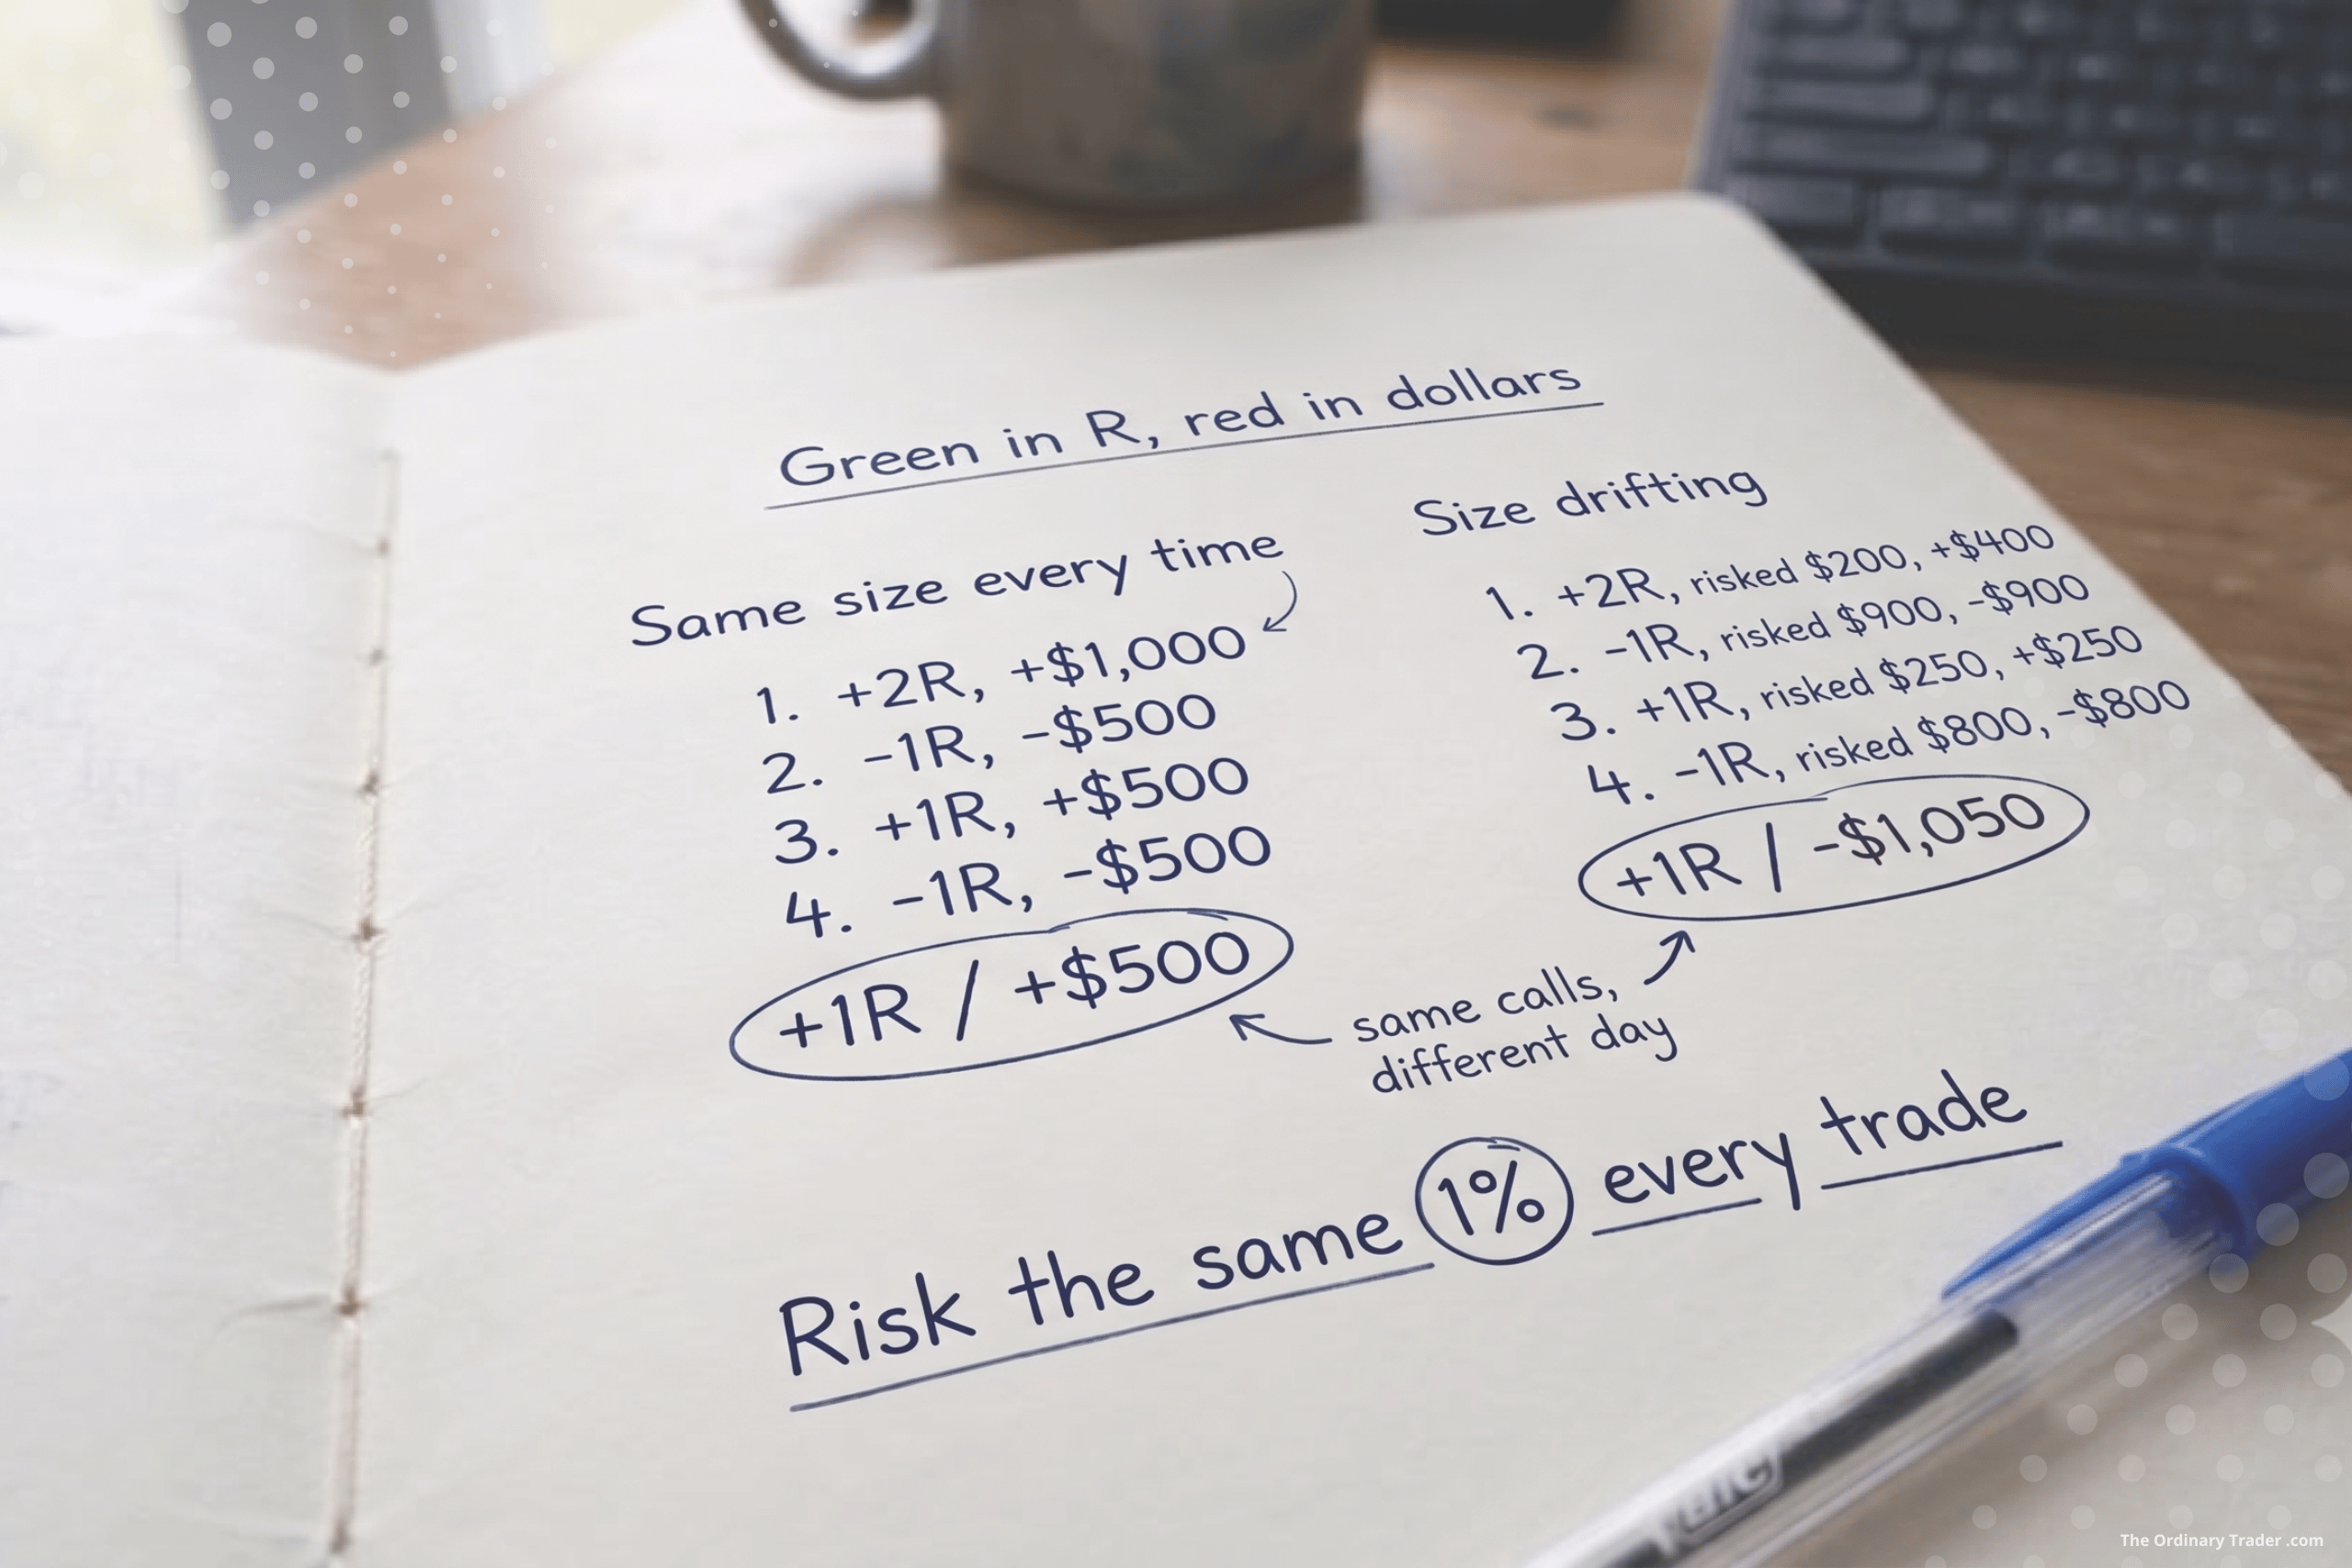
Tag Archive for: Trading Plan

For as long as I can remember, I’ve set myself a daily target. Make X a day. Hit the number, close the platform, get on with the rest of the day.

It felt sensible. A good number to aim for, something to measure each session against.

Lately, though, I’ve caught myself overtrading because of it.

Green, but not green enough

Here’s the pattern. I’m up on the day. A trade has played out and the P&L is green. But it’s short of the number.

So I take one more. Then, if that one doesn’t get me there, another. Each trade feels reasonable in the moment. But if I’m honest, the reason I’m taking it isn’t the chart. It’s the gap between where I am and where I said I’d be.

You can guess how it goes. A green day I could have banked turns into a smaller green day. Sometimes it turns into a red one. Sometimes it turns into drawdown.

The frustrating part is that none of this is news. Every trader has heard “don’t overtrade.” Knowing it and catching yourself doing it are not the same thing.

Every trader has heard “don’t overtrade.” Knowing it and catching yourself doing it are not the same thing.

Chasing a number, not a setup

Today a phrase popped into my head: it’s not about the money.

Something clicked. Maybe I’m not overtrading because the market is offering lots of setups. Maybe I’m overtrading because I’m chasing a number. Not a setup.

That’s a real difference. A setup is something the market shows you. It either meets your criteria or it doesn’t. A daily target is something you bring to the market. It has nothing to do with what price is doing. The market doesn’t know you’re short of your number, and it doesn’t care.

Once the number is in charge, the question you ask yourself changes. Instead of “does this meet my rules?” it becomes “can this get me the rest of the way?” Those two questions lead to very different trades.

What if there was no number?

So I’ve been sitting with a simple question. What if there was no number at all?

What if I took one trade, the one that properly meets my criteria, and accepted whatever it gave me? A win, a loss, a scratch. Done for the day.

It sounds almost too simple. That’s partly why it appeals. There’s nothing left to chase if the day is already finished.

A daily target is something you bring to the market. It has nothing to do with what price is doing

The obvious objection

One trade won’t add up to five or six green ones. That’s the first thing I thought, and it’s probably the first thing you thought too.

Fair. But I think that’s a sizing question, not a trade count question.

If I’m taking five or six trades to reach a daily figure, each one is sized small enough to allow for that many. Flip it around. Fewer trades, higher quality, larger size on the ones that meet my criteria. In theory, the same daily potential, with far fewer chances to give it back.

I want to be careful here, because “size up” is the kind of advice that gets people hurt. Bigger size means each loss lands harder too. This only works if a few things hold:

  • The criteria have to be strict. If “one quality trade” quietly becomes “one trade that looked okay,” it’s the same problem with more contracts.
  • The daily risk limit doesn’t move. Larger size on one trade has to fit inside the limit you already use, not replace it.
  • You have to be fine with a red day. One trade means some days end on a loss with nothing after it. That’s the deal.

None of this is proven yet. It’s a theory I’m about to test, not a result I’m reporting.

Making the plan the target

What changes most isn’t the maths. It’s what counts as a good day.

With a number, a good day is one where the P&L hits a figure. Without it, a good day is one where I executed the plan well. I waited for the setup. I took it at the right size. I managed it the way I said I would. Then I stopped.

That’s a target I can actually control. The market decides the P&L. I decide whether I followed my process.

It also fits how The Daily Trading Planner is meant to work. The planner is there to set your risk, trade limits and stop conditions before the session starts, while you’re calm. A trade limit of one is just a stricter version of the same idea.

If this sounds familiar

If you’ve got a daily target and you’ve ever turned a green day into a red one chasing it, try this before your next session. Go back through your journal and find the days you gave money back. Look at where the P&L was before the trade that started the slide.

Then ask yourself honestly. Was that trade taken because the setup was there, or because the number wasn’t?

You don’t need to scrap your target because I’m scrapping mine. But it’s worth knowing whether it’s working for you or against you.

Quality over quantity

So that’s where I’ve landed, for now. One trade (maybe 2). Proper criteria. Sized so the trades count. Accept what they give.

I don’t know yet how it’ll play out over a few weeks. I’ll log it and let the data show me.

It’s not about the money. It’s about doing the work well, and letting the money be whatever it turns out to be.
Ask a room of traders whether they have an edge and nearly every hand goes up. Ask them to write it down in one sentence, in a form another trader could follow, and most stop.

That gap is the problem. “Edge” is one of the most used and least defined words in trading. It gets used to mean confidence, or experience, or a feeling that things are going well lately. None of those can be measured. If you cannot measure it, you cannot tell whether you have one.

So start with a definition that does some work.

What an edge actually is

An edge is a repeatable set of conditions under which your outcomes, over a large enough sample, are better than random after costs.

Three parts. All of them matter.

Repeatable. You can specify the conditions in advance, in writing, and someone else could read them, apply them to the same chart and reach the same decision. If the conditions only become clear after the move has happened, they are not conditions. They are hindsight.

Over a sample. Not three trades. Not a good week. A run of outcomes large enough that luck starts to wash out. Any set of rules, however arbitrary, will produce a winning streak somewhere.

After costs. Commissions, exchange fees and slippage. On futures, costs are small per contract and constant per trade, which makes them easy to ignore and quietly fatal to small edges. A setup that makes 0.05R per trade before costs can make nothing at all after them.

Slippage is the difference between the price you expected and the price you got. It shows up most on stops and in fast markets.

Write it in a form that could be proved wrong

Here is the practical test. Can you write your edge as a statement specific enough to be tested?

“I trade market structure” is not testable. Neither is “I buy at Points of Interest when the context lines up.” They describe an approach, not a rule. Two traders could read them and take entirely different trades.

This is testable:

When price sweeps the prior day high and closes back below it within two candles on the 15 minute chart, I short with a stop above the sweep high and a target at the prior day low.

You may disagree with that rule. The point is that you could hand it to another trader, they could apply it to the last six months of charts, and you would both agree on which trades qualified.

The specificity is the point. A statement that vague cannot be proved wrong, which means it also cannot be proved right. And a belief that cannot be tested is not an edge. It is a preference.

Preferences are not worthless. Plenty of good traders start with one. But a preference that has never been counted is a hypothesis you have been paying to hold.

How many trades before you know anything

Honestly: more than you want.

Thirty trades tells you close to nothing. A 60% win rate over thirty trades is well within what a coin flip produces by chance. One hundred starts to be suggestive. Even then, a positive result may be luck, particularly if the whole record rests on two or three outsized trades.

That is uncomfortable, and worth sitting with. If you take two trades a day, one hundred trades is about ten weeks. That is the timescale on which the question gets answered. Not this week.

The numbers worth recording

For each testable statement, record these:

  • Number of trades taken
  • Win rate
  • Average win in R
  • Average loss in R
  • Expectancy per trade in R
  • Largest drawdown in R
  • Net result after costs

R is your risk on the trade, expressed as one unit. If you risk $200 and make $400, that is +2R. Using R rather than dollars means the record still means something when your position size changes.

Expectancy is the number that matters most. It is the average result per trade in R: multiply your win rate by your average win, then subtract your loss rate multiplied by your average loss. A method that wins 40% of the time with an average win of +2R and an average loss of -1R has an expectancy of +0.2R per trade. Modest, and enough.

Expectancy survives account size changes. Net dollars do not. A trader who doubles size after a good month can post a bigger P&L while the edge underneath quietly gets worse.

Two ways traders break their own test

The first is curve-fitting. You look at the trades that lost, add a condition that would have excluded them, and repeat until the statement describes your past trades almost perfectly. What you have built is not a rule. It is a description of history. If a rule carries more than about four conditions, ask which ones you added after seeing the results.

The second is quieter and more common. You take fifteen trades, hit a losing run, decide the rule needs adjusting, and start again. Do that a few times and the sample never accumulates. You have been trading for two years and you still have no record of anything. Not because you were undisciplined, but because you kept restarting the clock.

Both come from the same place: wanting the answer to be yes.

What to do this week

Write one statement. Entry condition, stop placement, target, timeframe, and the market you will trade it in. Read it back and ask whether another trader could apply it without ringing you.

Then take that trade, and only that trade, for the next fifty occurrences. Log the seven numbers. Do not adjust the rule mid-sample. If you find a genuine flaw, note it, finish the sample anyway, and test the revision as a separate statement.

At the end you will have one of three answers. It works. It does not. Or the sample is too small to say and you need another fifty.

That third answer is the one most traders skip past, and it is a real result. Not knowing yet, with a record building underneath you, is a better position than being certain with nothing written down.

Most traders have a checklist. Far fewer have one that has ever stopped them from taking a trade.

That gap is the whole problem. A checklist that has never once produced a “no” isn’t a filter. It’s decoration.

It’s worth being specific about why they fail, because the failure is usually in the design, not in you.

A checklist you abandon under pressure isn’t a checklist. It’s a document.

Why most trading checklists don’t work

They’re too long. Fifteen items reads fine on a quiet Sunday afternoon. At 09:32 with price moving, you’ll skim the first three and assume the rest. A checklist you abandon under pressure isn’t a checklist. It’s a document.

They’re written as aspirations. “Be patient.” “Trade with the trend.” “Wait for confirmation.” These sound like rules but they can’t be answered. You can convince yourself you’re being patient while clicking the mouse. Anything you can argue with, you will argue with.

They’re read after the decision. This is the quiet one. You see a setup, you decide you’re taking it, and then you glance at the list. At that point you’re not testing the trade, you’re looking for permission. The checklist becomes a rubber stamp for a decision you already made.

Nothing happens when an item fails. If “price is above my marked level” comes back as no, and you take the trade anyway, then the item was never a condition. It was a comment.

Fix those four things and you have something that works.

What a working item looks like

Every item has to be answerable in a couple of seconds, with a yes or a no, by someone who is not in a calm mood.

Not “is the trend strong.”

“Is price above the higher timeframe level I marked before the session opened.”

The second version has one answer. You marked the level before you had a position or an opinion about this specific trade, so the past version of you is doing the judging. That’s the point. You’re outsourcing the decision to a clearer-headed you.

Some more of the same conversion:

  • “Is there a clean setup” becomes “did price take out the high or low I marked, then close back inside it.”
  • “Is the risk sensible” becomes “is my stop where the idea is wrong, and is that distance inside the risk I wrote down this morning.”
  • “Am I trading my plan” becomes “is this one of the Points of Interest (POIs) on my chart before the session started.”

Notice what’s happened. The judgement has moved from during the trade to before it. That’s most of the work.

Keep it to five to seven items

Long checklists feel thorough. They aren’t, because they don’t survive contact with a live market.

Five to seven lines. One line each. If an item doesn’t earn its place, cut it.

And put the items that most often stop you at the top. This matters more than it sounds. If you only get through three lines before the impatience wins, those three lines still have to have done their job. The order isn’t cosmetic. It’s the failure plan.

You’ll only know which items those are by recording the trades you regret. Over a few weeks the pattern is usually consistent: two or three failures do most of the damage.

At least one item has to be about you

Every item so far is about the chart. Your state is a real variable, and it changes the quality of your decisions more than most people admit.

So include at least one line about the trader, not the market:

  • Have I already hit my daily loss limit.
  • Is this the third trade in twenty minutes.
  • Am I entering because the setup appeared, or because I want to be in something.

That last one is uncomfortable. It’s also the one that catches the most trades. Wanting to be in a position is not a reason. It just feels like one, because the feeling arrives at the same time the reason usually would.

The pre-session numbers those questions rely on, the daily loss limit, the trade limit, the point where you stop for the day, have to exist somewhere in writing before the session. The Daily Trading Planner on the site is one place to keep them. Anywhere works, as long as it’s written down and decided in advance.

Attach the consequence in advance

This is the part that makes the rest of it real.

A failed item means no trade. Not a smaller trade. Not a trade with a wider stop. No trade.

Decide it before the session, because in the moment it will always feel like an exception. This one is different. The item is being too strict. The spirit of the rule is satisfied even if the letter isn’t. Every trader has that conversation with themselves, and the only defence is having settled it earlier, when nothing was at stake.

A checklist without a consequence is a list of preferences.

A failed item means no trade. Not a smaller trade. Not a trade with a wider stop. No trade.

It works before entry and nowhere else

Once you’re in, the checklist is finished. Its job is done.

Re-reading it with a position open does nothing except reassure you, and reassurance is not information. The trade is either working or it isn’t, and that’s a question for your stop and your target. Used after entry, a checklist becomes a comfort blanket, something to hold while you avoid managing the trade you have.

Before entry, it’s a filter. After entry, it’s noise.

Why checklists exist at all

Aviation and surgery lean on checklists heavily, and the reasoning transfers. The point isn’t that the pilot has forgotten how to fly. It’s that under pressure, with time compressed and attention narrowed, anyone skips steps. Competence doesn’t protect you from that. Structure does.

You know what a good setup looks like. You will still take a bad one at 14:31 because you’re bored, or behind, or certain.

Write it tonight

Not this weekend. Tonight.

Five to seven items. One line each. Every one answerable yes or no in two seconds. The ones that most often stop you at the top. At least one about your state rather than the chart. And underneath, in your own handwriting, the consequence: any no means no trade.

Then print it. Put it where you can see it without opening anything, taped to the monitor, propped against the screen, somewhere your eye lands without a click.

The version that lives in a document you have to go and find is the version you’ll skip on exactly the day you needed it.

Copy trading changes one thing. It multiplies the outcome of your trade.

Every good decision lands on ten accounts instead of one. BUT…. so does every bad one.

When I first connected a trade copier across my prop accounts (I use TradeSyncer btw), the wins felt effortless. Then came the first proper red day, and I watched the same loss print ten times over. Nothing about my trading had changed. Only the exposure had.

Something clicked that day and I realised that taking the trade is the easy part. Managing the exposure around it is the real work. These are the ten rules I’ve settled on to help scale prop accounts when using trade copiers.

1. Go slow and let small wins compound

Scaling from one account to ten turns a normal 1R loss into a 10R hit to the book. Big days are great, but the losing days grow at exactly the same rate.

I’d rather bank a steady +1R across a group of accounts, day after day, than chase a big one and hand it back. Small wins compound. Big losses reset the clock.

2. Rotate and segment your accounts

You don’t need to trade every account all of the time. When the market is trending cleanly, running the full book makes sense. In choppy or uncertain conditions, it doesn’t.

I trade in batches of 5 to 10 accounts, take a win, then move to the next batch. Splitting by session works too, with half the accounts on the NY open and half in Asia or London. One bad session can then only touch part of the book.

3. Make a funded account your leader

I set a funded account as the leader and almost forget the evals exist. I trade the funded exactly as I normally would, and the evals follow.

Most eval mistakes come from the pressure of needing to pass. Remove that, trade well, and the evals convert as a by-product rather than the goal.

4. Use ratio multipliers on fresh evals

TradeSyncer lets you set a ratio multiplier on each follower. I’ll sometimes put a fresh eval on 2x, so a $200 risk on the leader becomes $400 on the eval. The funded keeps trading as normal while the eval reaches its outcome faster, pass or fail.

Be honest with yourself here. 2x doubles the losses too. It doesn’t make passing more likely. It makes the answer arrive sooner, which frees up the slot for the next attempt.

5. Build a bench of backup evals

Once a funded account has paid out, I start thinking about its replacement. Lucid allows five funded accounts at a time, so once mine are paying I add a few Lucid evals and work them towards funded.

Funded accounts eventually blow. That’s part of the job. When one does, a passed eval is ready to step straight in and there’s no downtime.

6. Know every firm’s rules before you copy

Not every firm allows copy trading, and some restrict trading the same strategy across firms. Hedging (holding opposite positions across accounts) is banned almost everywhere. Drawdown type, consistency rules and payout conditions all differ too.

Read the rules for every firm you connect. Accounts fail for rule breaches that have nothing to do with the quality of the trade.

7. Group accounts by rule set, not just by firm

An intraday trailing drawdown tracks your open profit in real time. A trade that runs $800 in your favour and comes back to breakeven has quietly raised your floor. On an end-of-day trailing account, it hasn’t.

Same trade, very different outcome. Keep accounts with matching size and drawdown mechanics together, so one trade means the same thing to every follower.

8. Put hard daily limits on every account

Every account gets a daily loss limit and a daily profit target (DPT). My funded accounts run a $1,000 loss limit against a $2,000 max drawdown, so one bad day can’t take more than half the buffer.

The profit target matters just as much, and it should be set in line with the firm’s consistency rule. On my evals the profit target is $3,000 (50k to 53k) with a 50% consistency rule, meaning no single day can make up more than half the total. That puts the DPT at $1,500. Hit it and the account locks for the day.

The same logic applies to any funded account with a consistency requirement on payouts. Set the target so a great day can never make you ineligible.

Check how the DPT interacts with your multipliers, too. A $750 day on the leader becomes $1,500 on a 2x eval, right at the cap.

9. Check the copies, not just the leader

Copiers are good, not perfect. Slippage, partial fills and the occasional disconnect happen.

I spot check follower fills against the leader after each session, and I know exactly where the flatten-all button is before I place a trade. Don’t assume every account did what the leader did.

10. Treat it like a business

Track eval fees against payouts, firm by firm. Some firms will earn their place, some won’t.

Stagger payout cycles so income doesn’t arrive in lumps, and spread across more than one firm, so a single firm changing its rules doesn’t take down the whole operation. It’s a book of accounts. Run it like one.

Same trade, managed better

None of this changes how I read a chart or where I enter. The Strategy is the same whether I’m trading one account or twenty.

What changes is everything around it: which accounts are live, how much each one can lose, and what’s waiting on the bench. That’s where copy trading is won or lost. Quietly, and mostly before the session starts.

A loss hurts in an obvious way. The number is red, the journal entry writes itself, and the lesson, if there is one, is right there on the chart. You feel it, you log it, you move on.

A big win is different. It feels like a reward. It feels like proof. And that is exactly what makes it dangerous, because the damage it does is quiet, it lands later, and it rarely shows up in the same session that caused it.

A loss keeps you honest. A win rewrites the story

When a trade goes against you, the feedback is clean. You either broke a rule or the market did something you could not have known. Either way, you are alert. You go back to the chart, you check the setup, you ask what you could have done better. A loss puts you in a questioning frame of mind, and questioning is where the learning happens.

A big win removes the question. The account is up, the screenshot looks great, and the brain does the laziest thing available: it assumes the process was sound because the outcome was good. But outcome and process are not the same thing. You can follow every rule and lose. You can break every rule and win. A win that came from a broken process is the most expensive kind, because it teaches you to do the wrong thing again, with more conviction.

That is the trap. The loss makes you cautious about a good decision. The win makes you confident about a bad one.

A win that came from a broken process is the most expensive kind, because it teaches you to do the wrong thing again, with more conviction.

The euphoria tax

There is a cost to feeling great at the screen, and it gets paid on the next trade.

After a big win, position size starts to creep. The risk that felt sensible last week now feels timid. You are playing with the house’s money, or so the story goes, and the rules that kept you disciplined start to look like they were holding you back. You widen a stop you would normally respect. You take a setup that is a B at best because the last A worked out so well. You see structure that is not really there, because you want to see it.

None of this feels reckless in the moment. It feels like confidence. It feels earned. That is the euphoria tax, and the bill is usually a giveback that wipes out a chunk of the win and a bit of your composure with it.

The asymmetry nobody plans for

Most traders prepare for losing days. They think about drawdown, they size their risk, they have a number that tells them to stop. Almost nobody prepares for a winning one.

So the winning day catches them undefended. There is no rule that says what to do when you are up 8R and buzzing. There is no stop condition for feeling unstoppable. The discipline that exists for losses simply does not exist for wins, and the market is happy to collect from whichever side you left open.

This is the gap the Daily Trading Planner is built to close. It makes you write down your profit target, your trade limit, and the point you walk away before the session starts, so the decision to stop is already made while you are calm rather than improvised while you are buzzing. A win cannot talk you into one more trade if you set the limit before the win existed. The same planning that caps your drawdown on a bad day caps your giveback on a good one.

Treat the win as a data point, not a verdict

The fix is not to celebrate less or to feel nothing. It is to give the winning session the same scrutiny you give the losing one.

Log it properly. Not just the R-multiple, but the why. Did the process produce this, or did the market simply move your way? Be honest. A 6R day that came from patience and a clean setup is worth repeating. A 6R day that came from oversizing into a lucky run is a warning, not a template, and the journal should say so.

Then go back to base size. The single most useful habit after a big win is to return to your normal risk on the very next trade, as if the win never happened. The setup does not know your account is up. The market does not owe you a continuation. Sizing up because you are winning is the same error as sizing up to win back a loss, just wearing a nicer outfit.

And space it out. If a win has you feeling certain, that certainty is the signal to slow down, not speed up. Step away from the screen. Let the buzz fade before you place the next trade, because trades placed on a high are trades placed by someone who is not really there.

The single most useful habit after a big win is to return to your normal risk on the very next trade, as if the win never happened.

The quiet point

A good trader is not someone who never loses. It is someone whose process survives both outcomes. Losses test your discipline in a way you can see coming. Wins test it in a way you cannot, which is precisely why they are the more revealing of the two.

So the next time the account jumps and the screenshot looks great, treat it the way you would treat a loss. Calmly. With a question rather than a conclusion. The win is not the reward. Holding your process steady through it is.

The setup you waited all session for finally prints. Structure broke, price swept the level, it pulled back into the zone. Textbook. Exactly what you wrote down. And you sit there. You watch the candle close. You tell yourself you want one more confirmation. The entry comes and goes, the trade runs without you, and you feel that familiar hollow thing in your chest.

Twenty minutes later you’re long something random. No zone, no plan, no reason you could explain to another trader. You just clicked. And it felt easy.

If that pattern sounds familiar, you already know the strange part. The trade that deserved your full attention got hesitation. The trade that deserved nothing got an instant yes. Most people read that as a discipline problem and try to fix it with willpower. It isn’t a discipline problem. It’s asymmetry, and willpower is the wrong tool for it.

The freeze and the click are the same problem

It’s tempting to treat these as two separate flaws. One is too cautious, the other too reckless. But they come from the same place. Neither the freeze nor the click is really about the chart. Both are your brain managing how a moment feels, not analysing what the market is doing.

The valid setup carries weight. You waited for it, you care about it, and somewhere underneath you know that if you take it and it loses, that one will sting. So your brain does what brains do with things that matter and feel risky. It stalls. It asks for more proof. It looks for the exit before you’ve even entered.

The bad trade carries no weight at all. There’s no plan to fail, no standard to fall short of, nothing riding on it. So there’s nothing to protect. The click is free.

Your brain is not trying to make you money. It’s trying to keep you comfortable. And those are not the same job.

Why the good setup gets the hesitation

Loss aversion does its loudest work exactly when the stakes feel real. The A+ setup is the one you’ve been waiting for, so a loss on it doesn’t feel like a normal cost of business. It feels like proof. Proof that you can’t read the market, that the waiting was pointless, that the whole approach is broken.

That’s a lot to put on one trade. No wonder you freeze.

So you ask for one more confirmation. Then another. You’re not actually gathering evidence at that point. You’re delaying the moment where you have to commit and be accountable for the outcome. The hesitation feels like caution. It’s usually fear wearing caution’s clothes.

And here’s the cruel bit. The more a setup matters to you, the more pressure you load onto it, and the more pressure you load on, the harder it is to pull the trigger. Your best setups become the ones you’re least able to take.

The hesitation feels like caution. It’s usually fear wearing caution’s clothes.

Why the bad trade gets the instant yes

Now look at the boredom side. You’ve been sitting on your hands for two hours. Nothing has set up. The discomfort of waiting builds quietly until it’s louder than any rule you wrote down. And a trade, any trade, makes that discomfort stop.

That’s the reward. Not the profit. The relief.

Clicking ends the waiting. It turns a passive, restless feeling into action, and action feels like progress even when it’s the opposite. The bad trade asks nothing of you because you’ve already decided, somewhere, that it doesn’t count. Low expectations, low pressure, easy click.

This is why people who can sit perfectly still through a slow morning suddenly fire into noise at lunchtime. Nothing changed on the chart. What changed is how long they’d been uncomfortable.

The asymmetry, stated plainly

Your brain protects you from the trades that matter and lets you run wild on the ones that don’t. The setups with the most thought behind them get the most resistance. The setups with no thought behind them slide straight through.

If you only fix the surface behaviour, you end up whipsawing. Force yourself to take the good ones and you start forcing marginal ones too. Ban yourself from the bad ones and you tense up so hard you miss the good ones as well. The behaviour isn’t the root. The asymmetry is.

decide when you’re calm and execute when you’re not.

Take the moment out of it

The fix is not more discipline in the moment. The moment is exactly where you’re weakest, because the moment is where the feeling lives. The answer is to make fewer decisions when it counts, by making them earlier when it doesn’t.

This is what the Daily Trading Planner is for. Before the session, when there’s no live trade pulling on you, you define the setup you’ll take, the risk, the invalidation, and the conditions that make you stand down. You decide once, calm, in advance. Then in the session your job is not to decide. It’s to recognise. The setup either matches what you wrote or it doesn’t.

That’s the whole shift. You move the decision out of the emotional moment and into a quiet one. When the A+ setup prints, you’re not weighing whether to be brave. You’re checking a box you already ticked an hour ago. Mechanical, not heroic.

And the impulsive click gets harder, because now there’s friction. If a trade isn’t in the plan, the rule isn’t “resist it.” The rule is “write down why you want it before you take it.” Most boredom trades don’t survive being written down. The honest sentence is usually “I’m bored and I want something to happen,” and seeing that on paper is enough to stop it.

You won’t think your way out of the freeze or the click in real time. Nobody does. What you can do is decide when you’re calm and execute when you’re not. The setup that matters becomes boring on purpose. The trade that doesn’t never gets the chance.

The loss that has nothing to do with the chart

The worst trades I have taken were not bad setups. They were good setups, taken on bad days. The signal was clean. The structure was there. The problem was the person reading it. Tired, flat, already three hours deep into a screen, looking for something to happen because sitting still felt like falling behind. That is not a trading mistake in the usual sense. It is a fatigue mistake wearing a trading costume.

For a long time I did not see it. A red day got filed under “the market was choppy” or “my entry was early.” Sometimes that was true. But often the real cause sat further upstream, in how I had slept, how long I had been staring, and whether I had any business being at the desk at all.

Real discipline includes the decision not to play.

Burnout does not arrive, it accumulates

Trading burnout is not a single dramatic moment. There is no alarm. It builds quietly, one slightly-too-long session at a time, until the screen stops being a tool and starts being a habit you cannot put down. The early signs are easy to talk yourself out of. You read the same candle five times and still could not say what it is telling you. You feel a small flare of irritation when price does not do what you wanted. You take a trade and feel relief rather than calm, because at least now something is happening. None of these are about the market. All of them are about you.

Screen fatigue compounds it. Hours of watching small movements narrows your view until the five-minute chart feels like the whole world. The longer you sit, the more reasonable a marginal setup starts to look, because your brain wants a reason to justify the time already spent. That is the trap. The cost of the seat makes you more likely to fill it badly.

The tells, named honestly

It helped me to write the signs down, plainly, so I could not pretend not to notice them. I am trading to feel productive rather than because the setup is there. I have moved my stop “just to give it room.” I am annoyed at the market, as if it owes me. I have stopped journaling because I do not want to see what is in there. I am refreshing the chart on my phone between other things. I cannot remember the last time I stepped away from the screen and felt fine about it.

Any one of these on its own is normal. Two or three stacked together is a signal, and it is a louder signal than most of the ones I draw on the chart. It says the edge today is not in the market. It is in not trading the market.

Stepping away is a skill, not a weakness

There is a quiet belief in trading culture that the serious people are the ones always at the desk. More screen time, more hours, more grinding. It sounds like discipline. Often it is the opposite. Real discipline includes the decision not to play. A professional in almost any precise craft knows that working tired produces worse work, and worse work in trading is not just unproductive, it is expensive. Stepping away on a bad day is not laziness or fear. It is risk management applied to the one variable nobody likes to admit is variable: yourself.

The hard part is that the decision has to be made before you sit down, not after the first loss. Once you are in the chair, fatigued and looking for action, you are the last person who should be deciding whether you are fit to trade.

So the question to ask before the session is not “what is the market doing.” It is “should I be here at all.”

Build the rule before you need it

This is where having something written down earns its place. I use the Daily Trading Planner to set the conditions of the day before the market gives me a reason to bend them. Risk limit, profit target, maximum number of trades, and the point at which I stop, full stop. Defined in the calm before, not the heat of during.

The planner is not really about the numbers. It is about removing the decision from the tired version of me. If the rule says two losses and I am done, then a third trade is not a judgement call I get to relitigate at the desk. It is already settled. The same goes for the days I should not start at all. A short pre-session check, an honest read of how I actually feel, and the permission, written in advance, to close the laptop and call it a flat day.

A flat day is not a wasted day. It is a protected account and a clearer head tomorrow. Over a year, the days I talked myself out of trading have saved me more than most of the days I traded well.

The quiet version of professional

None of this is dramatic. There is no breakthrough, no transformation. Just a slightly more honest relationship with my own state, and a rule that holds when I cannot. The market will be there tomorrow. It is open more hours than any person can sensibly trade, and it does not reward attendance. It rewards the trades you take well and punishes the ones you take tired. Knowing the difference, and being willing to act on it, is not a soft skill around the edges of trading. On a lot of days, it is the whole game.

So the question to ask before the session is not “what is the market doing.” It is “should I be here at all.” Some days the most disciplined thing on the screen is the decision to turn it off.

You open the economic calendar (usually forexfactory) before the session, scan for red folders, and find nothing. No CPI. No jobs report. No central bank speakers. The day looks clear.

Most traders read that as a green light. A safe day. Nothing to blow up the chart, nothing to catch them off guard.

It’s not that simple.

A day with no scheduled news behaves differently from a day with a report on it, and those differences are easy to miss until they’ve cost you.

What “safer” actually means

There’s a real kernel of truth in the safety idea. High-impact releases like CPI or non-farm payrolls can move the futures market hard and fast. On the S&P (ES) you can see 20 to 80 points in the first few minutes of a release. On the Nasdaq (NQ) it can be 100 to 400. When the number hits, price can move so fast that your stop doesn’t just get triggered, it fills at a worse price than you set, because there’s nobody there to fill you where you wanted.

Take the scheduled release away and that specific risk drops. No data drop means a much lower chance of a sudden spike that runs your stop before you can think. In that narrow sense, a no news day is safer.

But safer from a spike is not the same as easier to trade. Those are two different questions, and people collapse them into one all the time.

No news doesn’t mean clean charts

Here’s the part that catches people out. A news release isn’t only a risk. It’s also fuel.

Big releases bring participation. They give the market a reason to pick a direction and commit to it. Some of the cleanest trending days of the month are built on a catalyst, with price opening near one end of the range and closing near the other.

Strip the catalyst out and you often strip out the conviction with it. With fewer participants and thinner liquidity, price has less to push against. Moves start and stall. Every small push looks like the start of a trend and then fades. Stops get hunted in both directions because there isn’t enough order flow to hold a move together.

A news release isn’t only a risk. It’s also fuel.

That’s not a guarantee. A no news day that inherits a clear story from the session before, a strong close or a level everyone is watching, can still trend nicely. So it isn’t the absence of news that decides the day, it’s the absence of a story. An empty calendar just removes one of the most common reasons a market trends cleanly, which tilts the quiet day towards rotation and chop.

And most days are chop anyway. Markets spend far more time ranging and digesting than they do trending. A no news day just tilts the odds further in that direction.

Easy or hard depends on you, not the day

So is a quiet day easy or difficult? Honestly, that’s the wrong question.

A range-bound, low-conviction session is difficult if you trade it like a trend day. You chase the breakout, it fails, you flip, that fails too, and you’ve taken three trades in a market that was never going anywhere. That’s how a slow day quietly does more damage than a fast one.

The same day can be straightforward if you match your approach to it. Fewer trades. Tighter, more realistic targets. Patience for the spots where structure is actually clear, and a willingness to sit on your hands everywhere else. The market hasn’t changed its difficulty. You’ve changed whether you’re fighting it.

The calendar is the first thing I look at before a session, and this is where journaling earns its place. If you look back and see that your worst results cluster on quiet, newsless days, that’s not bad luck. That’s a mismatch between the conditions and how you traded them.

The quiet day before CPI is the one to watch

There’s one no news day that deserves special attention, and it’s the calmest-looking one of all. The day directly before a major release like CPI or an FOMC decision.

On paper, the calendar that day is empty. In practice, the market is already bracing for tomorrow.

Ahead of a big print, the professional desks do the opposite of what you’d expect. They take risk off rather than add it, because a surprise is a wild card they can’t control. On FOMC days the build-up has been clocked at 20% to 35% below average volume, with the daily range squeezing to a third or a half of a normal session. Liquidity thins out. The book gets shallow.

The result is a coil. Price grinds sideways in a tightening range while everyone waits. To an impatient trader it looks like a free, easy market. It is anything but. Thin conditions mean false breakouts fire constantly, and the liquidity that builds up sits at the obvious highs and lows of the range, right where stops cluster. It’s not unusual for price to sweep one side, then the other, clearing those stops before the real move ever arrives on the news.

Price grinds sideways in a tightening range while everyone waits.

So the day before CPI is a compression spring dressed up as a quiet afternoon. The mistake isn’t trading it. The mistake is trading it as though tomorrow isn’t coming, or worse, carrying a position into the print itself and hoping.

So, are no news days good for trading?

They’re not good or bad. They’re a different kind of day, and the job is to read which kind you’re in before you decide how to trade it, or whether to trade it at all.

The calendar isn’t a green light or a red one. It’s the first line of your plan. It tells you what kind of session to expect, so you can size and pace yourself to match. Read it that way, and a no news day stops being a trap and becomes just another set of conditions to trade well, or to leave alone.

You sit down to review yesterday’s trade. The chart is still there. The entry, the exit, the result, all logged. But the part you actually need has gone. What were you thinking when you moved that stop? Why did you nearly close the position early? You can’t quite remember.

That critical lost in detail is the whole reason I journal. And it is why I care more about the notes than the numbers.

I use TradeZella for this. It is a solid platform, and most people know it for the stats: win rate, average R, all the dashboards. Useful, but not what this post is about. I want to talk about the Notes side, where you capture what you were thinking and feeling before, during and after a trade. Tags and Strategies are worth their own post another day. For now, here is the template I use and how I actually use it.

That critical lost in detail is the whole reason I journal.

Three sections, one job

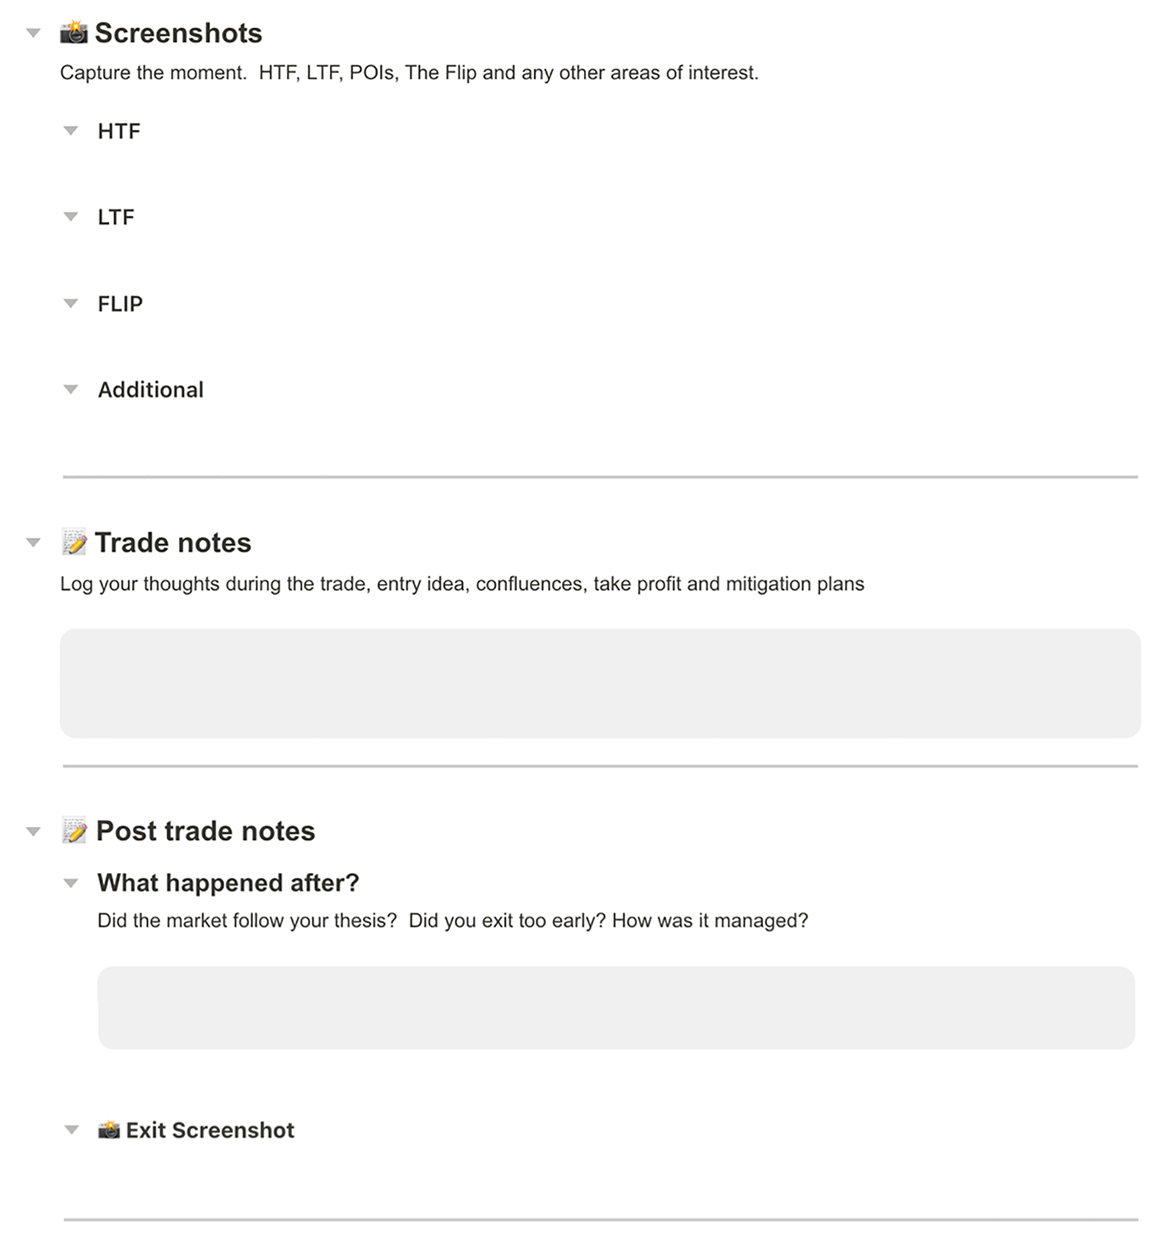
My template has three parts. Screenshots, Trade Notes, and Post Trade Notes. Each one captures a different slice of the same trade, and together they let me rebuild the whole thing later without relying on memory.


Screenshots: capture the moment

The first section is just images. I take a few as the trade develops, not all at the end.

A higher time frame shot (HTF, usually the 15 minute) to show the structure and the bias. A lower time frame shot (LTF, usually the 1 or 2 minute) for the detail of the entry. A zoomed-in shot of The Flip, because that is a key part of the setup I want to study again later. And an Additional slot for anything else worth keeping: the Path to Profit, a point of interest (POI) like a supply and demand zone (SNDR) or a fair value gap, whatever mattered on the day.

A fair value gap, by the way, is just the imbalance price leaves behind when it moves too fast to trade an area cleanly.

The reason I screenshot in the moment is that a chart looks completely different an hour later. Price has moved on, levels have been swept, and the thing that looked obvious at entry is buried. The screenshot freezes what I actually saw.

And this is the part most people skip. I write down how I am feeling.

Trade notes: the thinking and the feeling

This is the main section, and the one that does the most work.

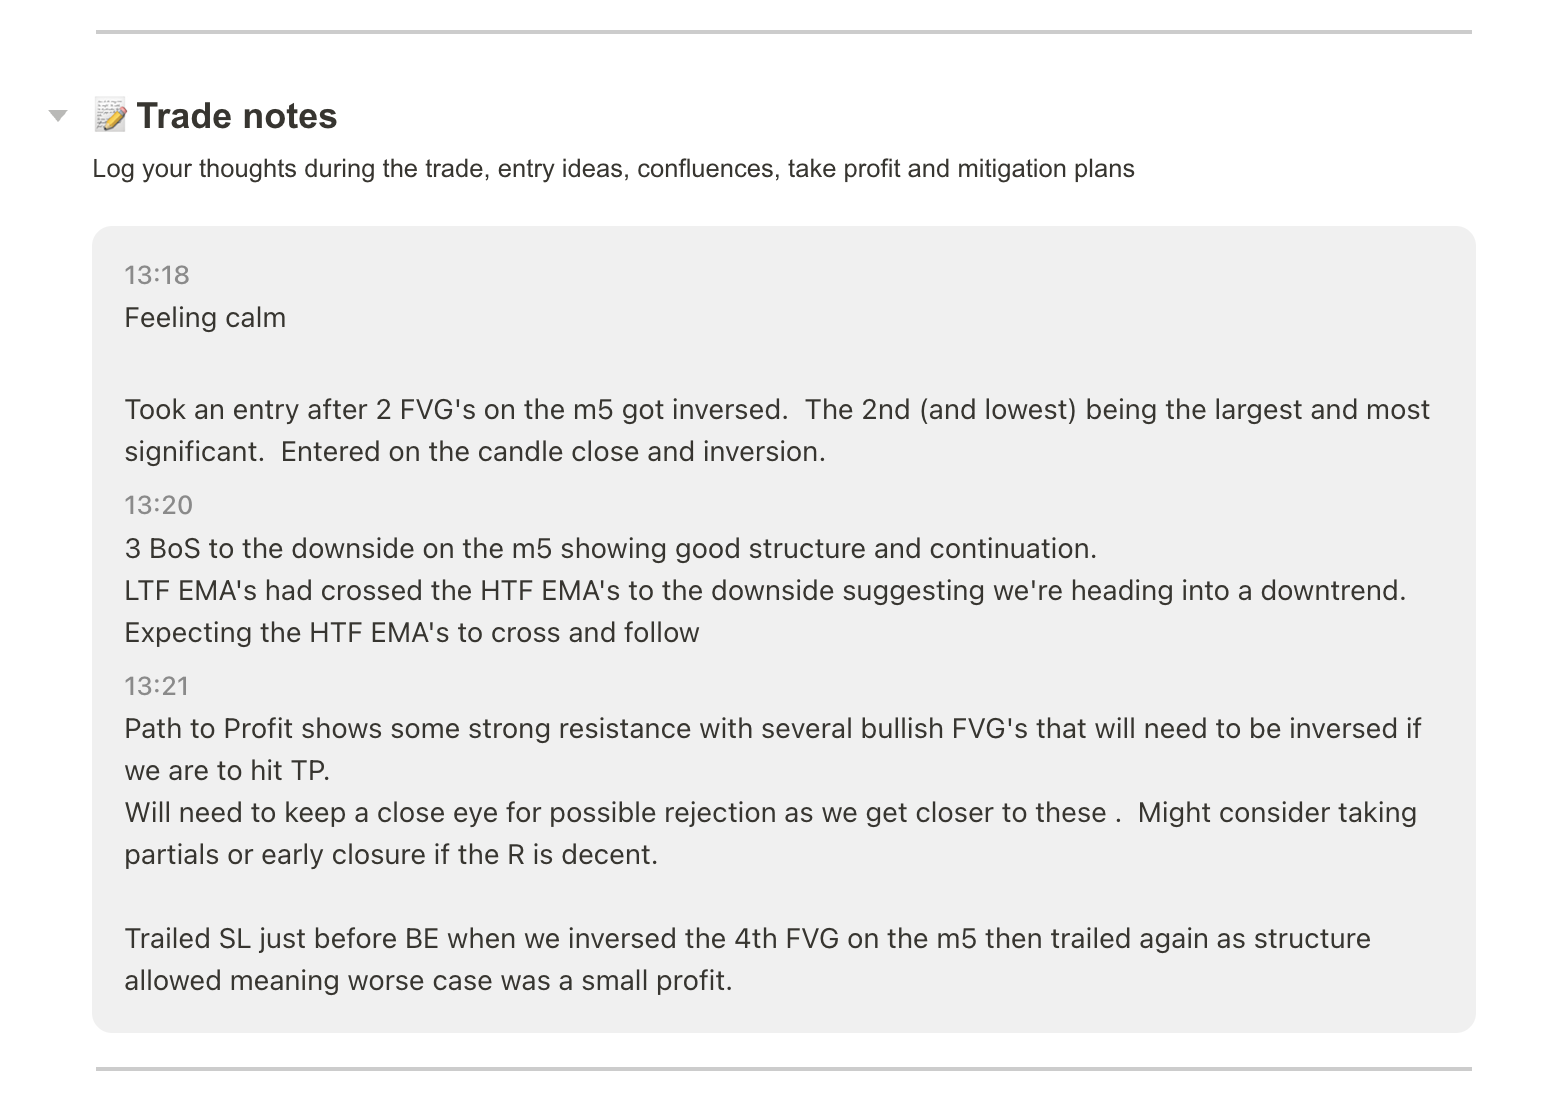
Here I write my thesis before I enter. The idea, the confluences, where I expect price to react, my take profit plan, and how I will manage the trade if it goes against me. Getting this down before entry matters, because it is the version of my thinking that has not yet been bent by an open position.

Then I keep adding to it as the trade runs. And this is the part most people skip. I write down how I am feeling.

That sounds soft. It is not. Emotion is where most of my mistakes start, and the only way to catch the pattern is to have it written down in your own words at the time. Read it back later and you can often see exactly where a feeling got in the way of a perfectly good setup. Sometimes it works the other way, and a note of unease turns out to be a warning sign you should have listened to.

Post trade notes: what actually happened

The last section is the review. I answer a few plain questions.

What happened after I took the trade? Did the market follow my thesis, or not? Did I exit too early, or enter too early? How did I manage it? Then the one that matters most: what would I do better next time, and if I could go back, what is the single piece of advice I would give myself?

This section also holds the exit screenshot. Did I hit my target, get stopped out, or close manually? I grab the final chart, and often what happened next too. Plenty of times I have hit TP1 and then watched price run on to take the previous day’s high. Capturing that teaches me something about where I am leaving money, and whether my targets are too conservative.

Capture it live, not from memory

I keep the journal open on my screen the entire session, next to the chart. I write as I go, in real time, as I enter and manage.

If you leave it until the evening, you do not really journal the trade. You are actually journalling your memory of the trade, which is a tidier, kinder, less accurate version of events. The hesitation gets smoothed over. The near-miss exit disappears. The thing you most needed to see is exactly the thing memory edits out.

You are actually journalling your memory of the trade, which is a tidier, kinder, less accurate version of events.

One trade, fully journalled, before the next

One rule I hold myself to. I do not take another trade until the first one is journalled and the lesson is captured.

Easier said than done, especially on an active session. But the moment you skip it “just this once,” the journal stops being a record and starts being a highlight reel. I treat finishing the journal as part of finishing the trade.

None of this is here to make me feel good about wins or bad about losses. It is here to make my behaviour visible. When I follow my rules, the results tend to take care of themselves. When I do not, the journal shows me exactly where. The chart only ever tells me what I did. The notes are the only place that remembers why.

You close the platform, glance at the day’s P&L, and it’s red. Not a blow-up day, just red. The annoying part is you didn’t trade badly. You actually had more wins than losses. You followed the plan. On paper it was a good day.  So what gives?

So why did your account go backwards?

I’ve had days exactly like that. The trades were fine. The sizing wasn’t.

This is the gap between a green day in R and a red day in dollars. It catches a lot of traders out, and once you’ve seen it you can’t unsee it.

R measures your decisions. Dollars measure your consistency. You can read the market well all day and still finish red if your sizing is all over the place.

Thinking in R, not just dollars

Quick definition first. R is just the amount you risk on a single trade. Risk $500 on a position and that $500 is your 1R. A trade that pays twice your risk is +2R. A full loss is -1R. R lets you talk about trades without the account size getting in the way, so a +2R win is a +2R win whether you’re trading $5,000 or $500,000.

Counting your day in R tells you one thing: whether your decisions were any good. Add up the R across every trade, and a positive number means the market paid you for the calls you made.

Dollars tell you something else. They tell you whether your sizing matched those decisions.

Most days the two agree. A green day in R is a green day in dollars. But they only stay in step if every R is worth about the same number of dollars. The moment your sizing drifts, they come apart.

Same trades, two different days

Here’s a simple example. Account of $50,000, risking 1% per trade, so 1R is $500. Four trades on the day.

Sized the same every time, at $500:

  • Trade 1: win, +2R, +$1,000
  • Trade 2: loss, -1R, -$500
  • Trade 3: win, +1R, +$500
  • Trade 4: loss, -1R, -$500

Net R: +1R. Net dollars: +$500. Green in both. Nothing clever happened. The sizing was just consistent.

Now the same four trades, the same R outcomes, but the sizing wandered. The wins landed on setups I was unsure about, so I went in small. The losses landed on the ones that looked obvious, so I went in heavy.

  • Trade 1: win, +2R, risked $200, +$400
  • Trade 2: loss, -1R, risked $900, -$900
  • Trade 3: win, +1R, risked $250, +$250
  • Trade 4: loss, -1R, risked $800, -$800

Net R: still +1R. The decisions were identical. Net dollars: -$1,050.

Red.

Same trades. Same calls. One day green, one day red. The only thing that changed was how much sat on the line each time.

Why sizing drifts without you noticing

That second day isn’t a freak event. It’s the pattern most of us fall into the moment we stop sizing by rule.

The setups that feel obvious tempt you to size up. They look like free money, so why not press? The trouble is the market doesn’t know which of your trades felt obvious. Some of those sure things lose, and now your biggest position is also your biggest loss.

The setups you’re unsure about tempt you to size down. Then it runs clean to target and you’ve collected a fraction of what the call was worth.

Yesterday leaks in too. After a win, confidence is up and the next position quietly creeps larger. I had this on a crude oil trade not long ago. An early win in the session made it far too easy to assume the next long would behave the same way. After a loss, the opposite happens and you shrink.

None of this is a decision you make on purpose. That’s what makes it dangerous. The R stays honest. The dollars quietly betray you.

Risk the same amount every time

The fix is boring, which is rather the point.

Risk the same percentage on every trade. I aim for 1% of my balance, every time, no matter how good the setup looks. The whole idea of an edge is that you’re right more often than you’re wrong across a large number of trades. You don’t know in advance which individual trade will be the winner. So betting more on the ones that feel good is just guessing, dressed up as conviction.

Fix the percentage and the dollars line up with the R. A green day in R becomes a green day in dollars, because that’s how the maths works when every R is the same size.

When one contract is too much

There’s a practical snag. Futures contracts come in fixed sizes, and sometimes one contract already risks more than 1%.

Take crude oil. One standard contract (CL) moves $10 a tick. The micro version (MCL) is a tenth of that, $1 a tick. Say your stop is 20 ticks and your 1% is $500.

With the standard contract, one CL risks $200 over that stop. To hit $500 you’d need 2.5 contracts, and you can’t trade half a contract. So you round to two ($400, or 0.8%) or three ($600, or 1.2%). Either way you’ve missed your number.

With micros, one MCL risks $20 over the same stop. $500 divided by $20 is exactly 25 micros. You land on 1% precisely.

That’s the case for dropping down to micros. Not because they’re safer, but because they let you size accurately when the bigger contract is too blunt an instrument. Most index futures work the same way, with a full contract and a micro at a tenth of the size.

Let the journal catch it

You log every session anyway. Add one column. Track the R and the dollars side by side, day by day.

Most days they’ll agree. The day you want to notice is the one where the R is green and the dollars are red. One of those is noise. A run of them is a message, and the message is that your sizing is the leak, not your strategy.

That matters because the instinct when the account bleeds is to go hunting for a better setup. But if the R is positive, the setups are doing their job. The thing to audit is how much you put on each one.

A note for funded traders

If you’re trading a prop firm evaluation, this stops being just an annoyance. A lot of firms run consistency rules, a cap on how much any single day or trade can contribute to your total profit. Size all over the place and one oversized winner can breach that limit, failing the challenge even on a profitable run. Same fix as always. Risk the same amount every time.

The quiet discipline

R measures your decisions. Dollars measure your consistency. You can read the market well all day and still finish red if your sizing is all over the place.

Sizing isn’t the exciting part of trading. It’s not a setup or an entry. It’s the bit that runs underneath, deciding whether your good decisions actually show up in the account. Get it consistent and the green days in R start turning into green days in dollars, which is the only place the difference ever really shows.