Tag Archive for: Risk

The number that feels like progress

You can win seven trades out of ten and still watch your account shrink.

It sounds wrong the first time you hear it. Win rate is the first number most new traders reach for, because it feels like a school grade. 70% sounds like a pass. 40% sounds like failure.

I spent my early months chasing that number. I wanted a strategy that was right more often than it was wrong, because being right felt like progress. The problem is that being right and making money are not the same thing. They are not even close.

Win rate is only half a sentence

A win rate on its own tells you how often you win. It says nothing about how much you win when you are right, or how much you lose when you are wrong. That second half is where your account is actually decided.

Here is the maths, kept simple. Say you win 70% of your trades, but your winners are small and your losers are large. You bank +0.5R on a win and give back -1R on a loss. Over ten trades, that is seven wins at +0.5R (+3.5R) and three losses at -1R (-3R). Net result: +0.5R across ten trades. A 70% win rate, and you have made almost nothing.

Now flip it. Say you win only 40% of your trades, but you let your winners run to +3R and cut your losers at -1R. Four wins at +3R (+12R) and six losses at -1R (-6R). Net result: +6R across ten trades, from a strategy that is wrong more often than it is right.

The trader who loses more often makes twelve times as much. Win rate did not tell you that. It could not.

The number that actually pays

The figure that matters is expectancy: what you can expect to make, on average, per trade. You work it out from both halves of the sentence.

Expectancy = (win rate x average win) – (loss rate x average loss)

Run the second example through it: (0.4 x 3) – (0.6 x 1) = 1.2 – 0.6 = +0.6R per trade. That is the number to know. It says that every time you place a trade to your plan, you can expect to make six tenths of your risk back, on average, over a large enough sample. Positive expectancy with enough repetitions is the whole game. Everything else is decoration.

This is why I stopped celebrating individual wins and stopped flinching at individual losses. A single trade tells me nothing. The average over a hundred trades tells me everything.

A single trade tells me nothing. The average over a hundred trades tells me everything.

What I track instead

Once you accept that expectancy is the destination, the day-to-day metrics change. These are the ones I keep in my journal now.

Average R per win and average R per loss, tracked separately. If my average loss is creeping above -1R, I am cutting too late, and no win rate will save me.

Expectancy per trade, in R, calculated across a rolling sample rather than a single day. One bad session does not move it much, which is the point.

Sample size. A positive expectancy over twelve trades is noise. Over a hundred and twenty, it is a signal. I do not trust any of my own numbers until the sample is big enough to mean something.

Process adherence, the one that is not about money. For every trade I log whether it was an A+ setup that met my filters, or whether I forced it. A profitable trade that broke my rules is still a bad trade. It just got lucky, and luck is not repeatable.

If you run the STRATEGY indicator, some of this is done for you. It has a stats panel that surfaces win rate, average RR and expectancy as you go, so you are not working the maths out by hand on a Sunday evening. The numbers matter more than where they come from, but having all three in front of you at once makes it harder to fixate on win rate and ignore the half of the sentence you would rather not look at.

Once you accept that expectancy is the destination, the day-to-day metrics change.

Why this is calmer, not just smarter

There is a quieter benefit to this. When your scorecard is win rate, every single loss feels like a mark against you, and you start trading to protect the number. You take profit early to lock in a win. You move your stop to avoid being wrong. Both habits shrink your average win and grow your average loss, which is exactly how a high win rate ends up with a flat account.

When your scorecard is expectancy and process, a loss inside your rules is not a failure. It is one of the six trades out of ten that you already knew would not work, paid for by the four that do. You stop needing to be right. You just need to be consistent.Once you accept that expectancy is the destination, the day-to-day metrics change.

Win rate is not useless. It is one input into expectancy, and a strategy with a dreadful win rate is hard to sit through even when the maths works. But on its own, as a measure of whether you are getting better, it is close to meaningless. Track the full sentence, not half of it.
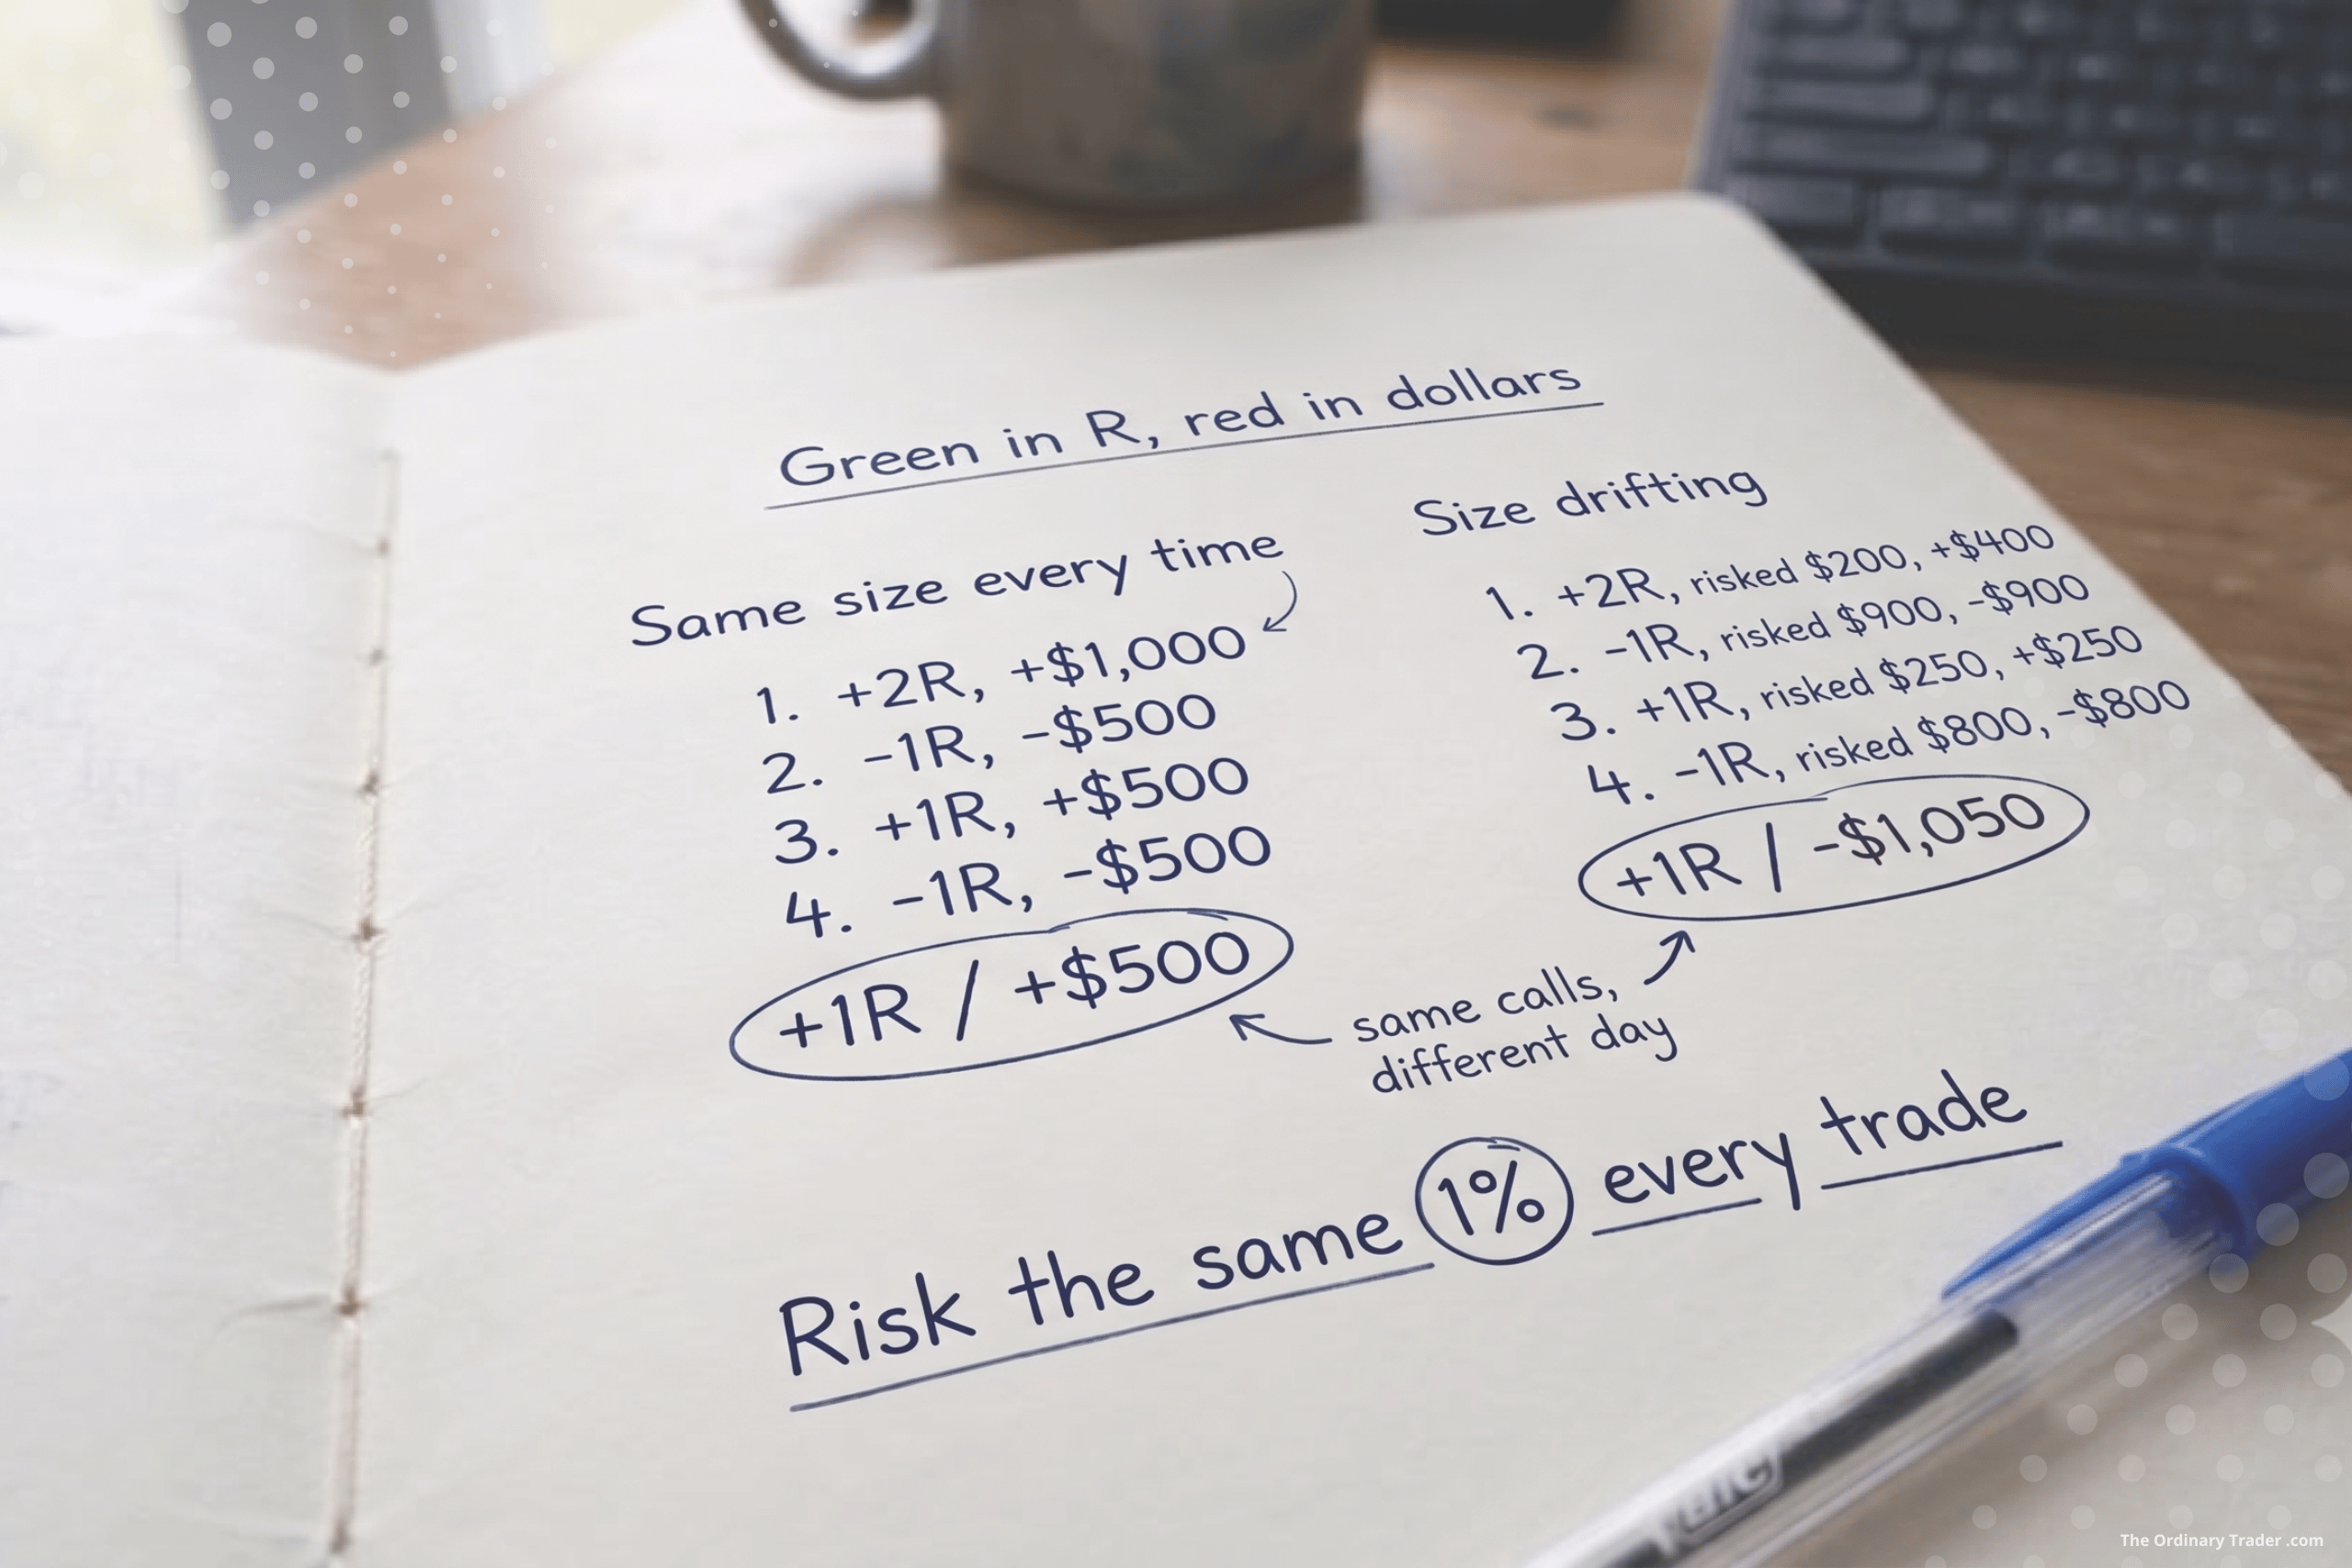
Where most people put their stop

Watch how a lot of traders set a stop and you will see the same move. They decide how much they are willing to lose, or how many points feels tolerable, and they put the stop there. Ten points because ten points feels okay. A round number because round numbers feel tidy. A fixed distance because that is what they always use.

The problem is that none of those reasons have anything to do with the trade. The market does not know or care how much you can afford to lose. It moves according to structure, liquidity, and where other people’s orders sit, and your comfort level is not on the chart. A stop placed to protect your feelings will sit in the wrong place almost every time, and the wrong place is where you get taken out of trades that were actually fine.

The market does not know or care how much you can afford to lose.

A stop answers one question

The real job of a stop is to answer a single question: at what point is my reason for being in this trade wrong?  Or to put it another way, at what point is my trade idea invalidated?

You entered for a reason. The market broke structure in your direction. Price tapped a Point of Interest and reacted. A level held. Whatever it was, there is a point on the chart where that reason no longer holds, where the story you entered on has clearly failed. That point is where your stop belongs, because that is where the trade is genuinely invalidated.

If you are long because a swing low held and the market broke upward, then a decisive move back below that low says the idea was wrong. The stop goes just beyond that low. Not at a round number nearby, not at the distance that feels comfortable, but at the level that, if hit, tells you honestly that this trade is done. When the stop marks invalidation, getting stopped out stops feeling like a personal failure and starts being useful information: the setup did not work, and you are out for a good reason.

Give the level room to breathe

Placing the stop on structure is the idea. Placing it too tight against the exact level is the common mistake.

Price does not respect levels to the tick. It overshoots. It wicks through a low, grabs the orders sitting just underneath, and reverses. That move even has a name in the method: a Liquidity Sweep. The stops resting exactly on the obvious level are the fuel for it. If your stop is sitting right on the round number or a hair below the swing low, you are parked in the most crowded spot on the chart, and you will get swept out of trades that then go on to work without you.

So the stop goes beyond the level, with enough room that a normal sweep does not take you out but a real break does. This is a judgement call, not a formula, and it is worth studying on your own charts: how far does price typically poke past a level before it means something. Give the trade room to survive the noise, while still cutting it the moment the structure genuinely breaks.

Set the stop where the idea dies. Give it room to survive the noise.

Now, and only now, size the trade

Here is the part that ties it together, and the reason the order matters so much. Once the stop is placed where the chart says it belongs, you have a fixed distance from entry to stop. That distance decides your size, not the other way round.

If the stop is far away, you take fewer contracts. If it is close, you can take more. What stays constant is the amount you are risking, whether you think of that as a flat dollar figure or 1R. The stop is set by the market. The size is the dial you turn to keep your risk where you want it.

This is the inversion most people never make. They pick a size they like and then hunt for a stop distance that fits it, which means jamming the stop somewhere that suits the position instead of the chart. Do it the other way. Find where the trade is wrong, put the stop just beyond it, then let that distance tell you how big you are allowed to be. If the resulting size feels too small, the honest answer is usually that the trade needs a wide stop and your risk cannot support a bigger position. That is the trade telling you the truth, and the fix is to take fewer contracts, never to move the stop in.

Why this is worth the discipline

A stop set on structure and sized to properly does two things at once. It gets you out of trades that are genuinely broken, at the point where staying in is just hope. And it keeps you in trades that are merely being noisy, because you gave the level enough room to breathe and sized so that the wider stop was still affordable.

The tight, comfortable, round-number stop does the opposite of both. It keeps you in busted trades because the level you cared about is already gone, and it throws you out of good ones because you parked right where the sweep was always going to run.

Set the stop where the idea dies. Give it room to survive the noise. Then size the trade to fit. Do it in that order and the stop stops being the thing you dread and becomes what it was always meant to be: the line that tells you, cleanly, when you are wrong.

Nasdaq confirmed this week that it will extend to 23-hour trading from 6 December, adding an overnight session from 9pm to 4am ET. NYSE already has SEC approval for a 22-hour day. CBOE is thinking about it too. The message from the exchanges is consistent: the market wants to run continuously, and the infrastructure is catching up.

The pitch from Nasdaq’s president is that this will “broaden investor access and expand wealth-building opportunities.” That framing deserves some scrutiny.

Because the assumption buried inside it is that access has been the problem. That retail traders have been sitting at the edge of opportunity, frustrated, waiting for the window to open. And that once it does, everything changes.

That’s not what the data on retail trading suggests. And it’s not what most traders experience honestly.

the reason people cycle through strategies and platforms and brokers – has never been that the market wasn’t open long enough.

Access was never the constraint

Here’s the thing: retail traders already have access to more market than they can trade well.

NQ futures run nearly 23 hours. Forex never closes. Crypto genuinely doesn’t sleep. The problem for the vast majority of retail traders – the reason the loss rates are what they are, the reason most accounts don’t grow, the reason people cycle through strategies and platforms and brokers – has never been that the market wasn’t open long enough.

It’s been execution. Risk management. Discipline. The ability to sit on your hands when there’s no setup. The ability to close a losing trade before it becomes an account-threatening one. The ability to follow a plan written before the session rather than the one written by emotion during it.

None of that improves because Nasdaq added seven hours to its schedule.

More hours is more noise

Every additional hour of a trading session is another hour of price action that needs to be filtered, assessed, and mostly ignored. The setups that meet every condition of a solid process are rare. That’s by design. A high-quality process produces few entries, not many.

The traders who struggle most with this aren’t the ones who haven’t found the right strategy. They’re the ones who can’t sit still. Who read inactivity as missed opportunity. Who treat every move the market makes as something that needs a response.

Extended hours won’t cure that. They’ll feed it. More candles, more movement, more moments where it looks like something is happening and the instinct says you should be in it. The always-on market is the ideal environment for overtrading, and overtrading is already one of the most reliable ways to drain an account slowly.

FOMO at scale

The psychological case for limiting your session is straightforward. A session you’ve prepared for, with levels identified, a plan in place, and a clear set of conditions for entry, is a session you can execute with some discipline. A session that runs for 23 hours is one where the conditions that justify trading are available for a fraction of the day, and everything else is noise you have to learn to ignore.

Most traders already struggle with FOMO in a six-and-a-half-hour window. Give the same trader 23 hours and you haven’t expanded their opportunity. You’ve expanded their exposure to the psychological pressure that already causes most of their problems.

The market open has its quirks. The first 30 minutes after the US open produces most of the volatility, most of the false breakouts, most of the traps for traders who haven’t done their preparation and are reacting to what they see rather than trading what they planned. The London open has its own behaviour. The overnight session, when it launches, will have its own characteristics – and those characteristics will take months to understand, probably longer.

Trading a new session before you understand how it moves is speculation, not process.

Most traders already struggle with FOMO in a six-and-a-half-hour window.

The mistake doesn’t change with the hours

What’s worth saying plainly is this: the reasons retail traders struggle are documented well enough. Overtrading, undersizing winners and oversizing losers, abandoning the plan mid-trade, chasing after losses, trading without preparation. These patterns appear across instruments, sessions, and market conditions.

They appear in bull markets and bear markets. They appear in volatile conditions and slow ones. They appear whether the exchange is open for six hours or twenty-three.

The opportunity to make better decisions is already inside your existing session. More often than not, the trades that should be taken are clear. The ones that shouldn’t are clear too – in hindsight, at least, once the position is closed at a loss.

The work is making that clarity available before the trade. Not after.

The edge has never been about being in the market the most.

What doesn’t change

Nasdaq’s 23-hour schedule is interesting news. The geopolitical argument for it is real – markets have repeatedly been caught closed when significant events happened overnight, and the demand for pricing in real time is legitimate. For certain categories of investor and institution, the extension solves an actual problem.

For the retail trader working on their process, it changes almost nothing. The edge has never been about being in the market the most. It’s been about being in the right trade, at the right time, sized correctly, with a defined exit.

You can do all of that in a two-hour window, if the conditions are right. You can fail to do all of it across twenty-three hours too.

My partner can now tell when I’m about to lose an argument. Not because I raise my voice. Because I go quiet, stare at the middle distance, and clearly start “reading the situation and waiting for a better entry.”

This is what trading does to you. It leaks. You spend enough hours watching charts and managing risk, and the habits stop staying at the desk. They follow you to the dinner table, into the school run, into the small daily negotiations of living with other people. Mostly that is a good thing. Occasionally it is deeply annoying for everyone around you.

Let me poke fun at us for a second before I defend us.

Yes, we are a bit much

We talk in R-multiples. We describe a good day as “low and slow”, and how a trump tweet killed your setup.   We have opinions about candle colours. Some of us have built a command centre of six monitors to trade an instrument that requires roughly one decision a day. We say “it would be interesting to monitor that” about things that are not worth monitoring, like whether the bins go out on a Tuesday or a Wednesday.

The stereotype exists for a reason, and I am not above it. I have absolutely paused a family conversation to “just check one thing.” and then ending up watching candles print for the next hour. I have described my own toddler’s tantrum as “a liquidity grab.” Nobody asked me to. I did it anyway.

So no, I’m not here to tell you trading makes you a better person by default. It does not. But the actual skills, the unglamorous ones underneath the jargon, turn out to travel surprisingly well into family life. Far better than the jargon does.

The old me heard a complaint and fired back instantly, full port, no stop loss.

Patience stops being a trading word

The first thing trading teaches you, if you let it, is that doing nothing is a position.

You wait for the setup. You sit on your hands through twenty moves that look tempting and are not. You learn that the urge to act is not the same as a reason to act.

That single habit has done more for my relationship than any book on communication. The old me heard a complaint and fired back instantly, full port, no stop loss. The newer me has learned to wait for the actual point to form. Most arguments at home are like most setups on the chart. If you wait a beat, the thing you were about to react to turns out not to be the thing that matters.

Not passive. Not avoiding it. Just not entering on the first candle.

Risk management is really just not betting the house on the dishwasher

Here is the unsexy heart of trading: you decide, in advance, how much you are willing to lose on any one idea. Then you stick to it, even when you are convinced you are right.

You are always convinced you are right. That is the point. The rule exists precisely for the moments your conviction is loudest.

Drop that into family life and it changes everything. Is being correct about whose turn it was to load the dishwasher worth risking the whole evening? You can size that position. Small. Tiny, actually. Some disagreements are a 0.25% risk and you treat them that way. Others genuinely matter, and you commit properly. Knowing the difference, and deciding the size before you are emotional rather than during, is the whole game in both places.

The trader who blows the account is the one who turns every trade into the trade. The same person, at home, turns every disagreement into the disagreement. I have been that person. The account and the evening both recover faster when you don’t.

Cutting a loss instead of doubling down

Every trader knows the temptation to add to a losing position to “prove” it will come back. We have a name for the family version. It is called continuing to argue your point after everyone, including you, has quietly realised you are wrong.

Revenge trading and the angry follow-up text are the same instinct wearing different clothes. The discipline that stops me sending the second, worse message at 11pm is the exact discipline that stops me clicking buy again after a stopout. Accept the loss. Log it. Move on. Apologise if the loss was your fault, which, statistically, it often is.

Turns out the people I live with do not care about my win rate or the trump tweet that killed my setup.

The review matters more than the result

The habit I value most is the boring one. After a trading session I write down what happened and why, without flinching, win or lose.

I have started doing a quieter version of this after a rough day at home. Not ruminating too much. Just asking honestly: what was actually going on there, and what would I do differently. Process over outcome. You stop scoring conversations by who won and start scoring them by whether you showed up the way you wanted to.

Turns out the people I live with do not care about my win rate or the trump tweet that killed my setup. They care whether I’m present, steady, and not staring at a phone under the table. Funny how the brand line about ordinary process and real progress applies to a marriage roughly as well as it applies to a chart.

The honest bit

Trading will not fix your relationships. If anything, untreated, it gives you a new vocabulary to be annoying in. But the skills underneath it, patience, sizing your bets, cutting losses, reviewing honestly, are just life skills that happen to be taught very efficiently by a market that charges you money for getting them wrong.

The market made me calmer at home mostly by making me poorer every time I wasn’t. That is a harsh teacher, but an effective one.

Now if you’ll excuse me, I have a family conversation about no phones at the dinner table.

You open the economic calendar (usually forexfactory) before the session, scan for red folders, and find nothing. No CPI. No jobs report. No central bank speakers. The day looks clear.

Most traders read that as a green light. A safe day. Nothing to blow up the chart, nothing to catch them off guard.

It’s not that simple.

A day with no scheduled news behaves differently from a day with a report on it, and those differences are easy to miss until they’ve cost you.

What “safer” actually means

There’s a real kernel of truth in the safety idea. High-impact releases like CPI or non-farm payrolls can move the futures market hard and fast. On the S&P (ES) you can see 20 to 80 points in the first few minutes of a release. On the Nasdaq (NQ) it can be 100 to 400. When the number hits, price can move so fast that your stop doesn’t just get triggered, it fills at a worse price than you set, because there’s nobody there to fill you where you wanted.

Take the scheduled release away and that specific risk drops. No data drop means a much lower chance of a sudden spike that runs your stop before you can think. In that narrow sense, a no news day is safer.

But safer from a spike is not the same as easier to trade. Those are two different questions, and people collapse them into one all the time.

No news doesn’t mean clean charts

Here’s the part that catches people out. A news release isn’t only a risk. It’s also fuel.

Big releases bring participation. They give the market a reason to pick a direction and commit to it. Some of the cleanest trending days of the month are built on a catalyst, with price opening near one end of the range and closing near the other.

Strip the catalyst out and you often strip out the conviction with it. With fewer participants and thinner liquidity, price has less to push against. Moves start and stall. Every small push looks like the start of a trend and then fades. Stops get hunted in both directions because there isn’t enough order flow to hold a move together.

A news release isn’t only a risk. It’s also fuel.

That’s not a guarantee. A no news day that inherits a clear story from the session before, a strong close or a level everyone is watching, can still trend nicely. So it isn’t the absence of news that decides the day, it’s the absence of a story. An empty calendar just removes one of the most common reasons a market trends cleanly, which tilts the quiet day towards rotation and chop.

And most days are chop anyway. Markets spend far more time ranging and digesting than they do trending. A no news day just tilts the odds further in that direction.

Easy or hard depends on you, not the day

So is a quiet day easy or difficult? Honestly, that’s the wrong question.

A range-bound, low-conviction session is difficult if you trade it like a trend day. You chase the breakout, it fails, you flip, that fails too, and you’ve taken three trades in a market that was never going anywhere. That’s how a slow day quietly does more damage than a fast one.

The same day can be straightforward if you match your approach to it. Fewer trades. Tighter, more realistic targets. Patience for the spots where structure is actually clear, and a willingness to sit on your hands everywhere else. The market hasn’t changed its difficulty. You’ve changed whether you’re fighting it.

The calendar is the first thing I look at before a session, and this is where journaling earns its place. If you look back and see that your worst results cluster on quiet, newsless days, that’s not bad luck. That’s a mismatch between the conditions and how you traded them.

The quiet day before CPI is the one to watch

There’s one no news day that deserves special attention, and it’s the calmest-looking one of all. The day directly before a major release like CPI or an FOMC decision.

On paper, the calendar that day is empty. In practice, the market is already bracing for tomorrow.

Ahead of a big print, the professional desks do the opposite of what you’d expect. They take risk off rather than add it, because a surprise is a wild card they can’t control. On FOMC days the build-up has been clocked at 20% to 35% below average volume, with the daily range squeezing to a third or a half of a normal session. Liquidity thins out. The book gets shallow.

The result is a coil. Price grinds sideways in a tightening range while everyone waits. To an impatient trader it looks like a free, easy market. It is anything but. Thin conditions mean false breakouts fire constantly, and the liquidity that builds up sits at the obvious highs and lows of the range, right where stops cluster. It’s not unusual for price to sweep one side, then the other, clearing those stops before the real move ever arrives on the news.

Price grinds sideways in a tightening range while everyone waits.

So the day before CPI is a compression spring dressed up as a quiet afternoon. The mistake isn’t trading it. The mistake is trading it as though tomorrow isn’t coming, or worse, carrying a position into the print itself and hoping.

So, are no news days good for trading?

They’re not good or bad. They’re a different kind of day, and the job is to read which kind you’re in before you decide how to trade it, or whether to trade it at all.

The calendar isn’t a green light or a red one. It’s the first line of your plan. It tells you what kind of session to expect, so you can size and pace yourself to match. Read it that way, and a no news day stops being a trap and becomes just another set of conditions to trade well, or to leave alone.

You close the platform, glance at the day’s P&L, and it’s red. Not a blow-up day, just red. The annoying part is you didn’t trade badly. You actually had more wins than losses. You followed the plan. On paper it was a good day.  So what gives?

So why did your account go backwards?

I’ve had days exactly like that. The trades were fine. The sizing wasn’t.

This is the gap between a green day in R and a red day in dollars. It catches a lot of traders out, and once you’ve seen it you can’t unsee it.

R measures your decisions. Dollars measure your consistency. You can read the market well all day and still finish red if your sizing is all over the place.

Thinking in R, not just dollars

Quick definition first. R is just the amount you risk on a single trade. Risk $500 on a position and that $500 is your 1R. A trade that pays twice your risk is +2R. A full loss is -1R. R lets you talk about trades without the account size getting in the way, so a +2R win is a +2R win whether you’re trading $5,000 or $500,000.

Counting your day in R tells you one thing: whether your decisions were any good. Add up the R across every trade, and a positive number means the market paid you for the calls you made.

Dollars tell you something else. They tell you whether your sizing matched those decisions.

Most days the two agree. A green day in R is a green day in dollars. But they only stay in step if every R is worth about the same number of dollars. The moment your sizing drifts, they come apart.

Same trades, two different days

Here’s a simple example. Account of $50,000, risking 1% per trade, so 1R is $500. Four trades on the day.

Sized the same every time, at $500:

  • Trade 1: win, +2R, +$1,000
  • Trade 2: loss, -1R, -$500
  • Trade 3: win, +1R, +$500
  • Trade 4: loss, -1R, -$500

Net R: +1R. Net dollars: +$500. Green in both. Nothing clever happened. The sizing was just consistent.

Now the same four trades, the same R outcomes, but the sizing wandered. The wins landed on setups I was unsure about, so I went in small. The losses landed on the ones that looked obvious, so I went in heavy.

  • Trade 1: win, +2R, risked $200, +$400
  • Trade 2: loss, -1R, risked $900, -$900
  • Trade 3: win, +1R, risked $250, +$250
  • Trade 4: loss, -1R, risked $800, -$800

Net R: still +1R. The decisions were identical. Net dollars: -$1,050.

Red.

Same trades. Same calls. One day green, one day red. The only thing that changed was how much sat on the line each time.

Why sizing drifts without you noticing

That second day isn’t a freak event. It’s the pattern most of us fall into the moment we stop sizing by rule.

The setups that feel obvious tempt you to size up. They look like free money, so why not press? The trouble is the market doesn’t know which of your trades felt obvious. Some of those sure things lose, and now your biggest position is also your biggest loss.

The setups you’re unsure about tempt you to size down. Then it runs clean to target and you’ve collected a fraction of what the call was worth.

Yesterday leaks in too. After a win, confidence is up and the next position quietly creeps larger. I had this on a crude oil trade not long ago. An early win in the session made it far too easy to assume the next long would behave the same way. After a loss, the opposite happens and you shrink.

None of this is a decision you make on purpose. That’s what makes it dangerous. The R stays honest. The dollars quietly betray you.

Risk the same amount every time

The fix is boring, which is rather the point.

Risk the same percentage on every trade. I aim for 1% of my balance, every time, no matter how good the setup looks. The whole idea of an edge is that you’re right more often than you’re wrong across a large number of trades. You don’t know in advance which individual trade will be the winner. So betting more on the ones that feel good is just guessing, dressed up as conviction.

Fix the percentage and the dollars line up with the R. A green day in R becomes a green day in dollars, because that’s how the maths works when every R is the same size.

When one contract is too much

There’s a practical snag. Futures contracts come in fixed sizes, and sometimes one contract already risks more than 1%.

Take crude oil. One standard contract (CL) moves $10 a tick. The micro version (MCL) is a tenth of that, $1 a tick. Say your stop is 20 ticks and your 1% is $500.

With the standard contract, one CL risks $200 over that stop. To hit $500 you’d need 2.5 contracts, and you can’t trade half a contract. So you round to two ($400, or 0.8%) or three ($600, or 1.2%). Either way you’ve missed your number.

With micros, one MCL risks $20 over the same stop. $500 divided by $20 is exactly 25 micros. You land on 1% precisely.

That’s the case for dropping down to micros. Not because they’re safer, but because they let you size accurately when the bigger contract is too blunt an instrument. Most index futures work the same way, with a full contract and a micro at a tenth of the size.

Let the journal catch it

You log every session anyway. Add one column. Track the R and the dollars side by side, day by day.

Most days they’ll agree. The day you want to notice is the one where the R is green and the dollars are red. One of those is noise. A run of them is a message, and the message is that your sizing is the leak, not your strategy.

That matters because the instinct when the account bleeds is to go hunting for a better setup. But if the R is positive, the setups are doing their job. The thing to audit is how much you put on each one.

A note for funded traders

If you’re trading a prop firm evaluation, this stops being just an annoyance. A lot of firms run consistency rules, a cap on how much any single day or trade can contribute to your total profit. Size all over the place and one oversized winner can breach that limit, failing the challenge even on a profitable run. Same fix as always. Risk the same amount every time.

The quiet discipline

R measures your decisions. Dollars measure your consistency. You can read the market well all day and still finish red if your sizing is all over the place.

Sizing isn’t the exciting part of trading. It’s not a setup or an entry. It’s the bit that runs underneath, deciding whether your good decisions actually show up in the account. Get it consistent and the green days in R start turning into green days in dollars, which is the only place the difference ever really shows.

Should You Take 1R or Let It Run?

Most new traders focus almost entirely on entries. They refine confirmations, tweak structure rules, and optimise timing. But very quickly you realise something more important. Your exit strategy determines your expectancy.

Let’s walk through a clean example using simple numbers. No complicated formulas. Just clear logic.

We will assume the same core distribution throughout so every strategy is compared fairly.

The Starting Distribution

Across a large sample of trades:

  • 40% lose and hit full stop at -1R
  • 30% reach 1R but fail to extend further
  • 30% extend beyond 1R and can reach 1.5R

This is the raw behaviour of your system before deciding how to exit.

Now let’s compare four exit strategies using this same base data.

Strategy 1: Fixed 1R Take Profit

In this model you close the entire position at 1R. No partials. No trailing. No runners.

Using the base distribution:

  • 60% of trades reach at least 1R
  • 40% lose -1R

So expectancy is:

  • 60% × +1R = +0.60R
  • 40% × -1R = -0.40R

Total = +0.20R per trade

This is clean and efficient. Your edge here is accuracy. You monetise the fact that most trades reach 1R.

Strategy 2: 50% Partial at 1R, Runner to 1.5R

This is the classic hybrid approach.

When price hits 1R:

  • Close 50% for +0.5R
  • Move stop to break even

If the trade extends to 1.5R:

  • Remaining half earns +0.75R
  • Total win = +1.25R

If price reverses after 1R:

  • Remaining half stops at break even
  • Total win = +0.5R

Using our distribution:

  • 30% hit 1.5R → +1.25R
  • 30% stall after 1R → +0.5R
  • 40% lose → -1R

Now calculate:

  • 30% × 1.25R = +0.375R
  • 30% × 0.5R = +0.15R
  • 40% × -1R = -0.40R

Total = +0.125R per trade

Still profitable. But lower than the simple 1R model.

Why? Because only 30% of trades meaningfully extend. The runner frequency is not high enough to compensate for halving position size.

Strategy 3: Full Position Runner to 1.5R

Now we remove partials. The entire position aims for 1.5R.

If price reaches 1R but fails to continue, you move stop to break even and make nothing.

Distribution becomes:

  • 30% hit 1.5R → +1.5R
  • 30% reach 1R but reverse → 0R
  • 40% lose → -1R

Expectancy:

  • 30% × 1.5R = +0.45R
  • 30% × 0R = 0
  • 40% × -1R = -0.40R

Total = +0.05R per trade

You increased reward size but reduced realised wins. That trade off reduced expectancy.

Strategy 4: Structure Based Trailing

Now we remove the artificial 1.5R cap. Instead of targeting a fixed multiple, you trail behind structure and allow the market to decide.

To keep assumptions realistic, let’s use this distribution:

  • 40% lose → -1R
  • 30% reach 1R and then stop at break even → 0R
  • 20% trend moderately → +1.5R
  • 10% become strong runners → +2.5R

Now calculate:

  • 20% × 1.5R = +0.30R
  • 10% × 2.5R = +0.25R
  • 30% × 0R = 0
  • 40% × -1R = -0.40R

Total = +0.15R per trade

This improves on partials and fixed 1.5R runners, but still does not beat the simple 1R model under these conditions.

Comparing All Four

Using consistent assumptions:

  • Fixed 1R → +0.20R
  • Partials + 1.5R cap → +0.125R
  • Full 1.5R runner → +0.05R
  • Structure trailing → +0.15R

Under this distribution, the simplest strategy wins.

What This Teaches a New Trader

Risk reward ratio alone means nothing. A 1:1.5 target is not automatically superior to 1:1. What matters is how often price actually extends.

Your optimal exit depends on the behaviour of your market.

In rotational conditions:

  • Moves stall quickly
  • Pullbacks are deep
  • Extensions are limited

That profile favours harvesting 1R consistently.

In strong trending conditions:

  • Pullbacks are shallow
  • Structure stair steps cleanly
  • Large extensions are common

That profile favours structure based trailing and uncapped runners.

The mistake is using the same exit logic in both environments.

How to Decide With Data

Track one simple metric over your next 50 trades:

Maximum favourable excursion measured in R.

If most trades rarely exceed 1.5R before reversing, fixed 1R exits are likely optimal.

If a meaningful percentage regularly reach 2R or more, you may be capping your distribution too early.

The goal is not to maximise reward on a single trade. The goal is to optimise your overall distribution.

Sometimes the ordinary 1R is the most efficient solution.

Sometimes the market is offering a trend and you need to step aside and let it pay you.

The numbers will tell you which environment you are in.

Most people come into trading looking for excitement. Fast moves. Big wins. Adrenaline. That expectation is usually where things start to go wrong.

The best trading days I’ve had are forgettable. No drama. No stories worth telling. Just routine.

I sit down at the same time. I look at the same markets. I follow the same process. There’s nothing clever or impressive about it.

When a trade works, it doesn’t feel amazing. It feels expected. When it doesn’t, it’s accepted, logged, and left alone.

Emotion is expensive in trading. Excitement leads to oversizing. Frustration leads to overtrading. Boredom, it turns out, is much safer.

As my routine became more consistent, I felt less during the session. That isn’t a flaw. That’s the point.

I’m not trying to read the market in real time. I’m trying to execute a process I’ve already thought through. The thinking happens before the session. During the session, I follow instructions.

Repetition builds trust. Trust in the setup. Trust in the risk. Without that, every trade feels like a gamble rather than a decision.

Most deviations start small. A slightly early entry. A slightly wider stop. In the moment, they don’t feel like mistakes.

They show up later in the journal. Not because the trade lost, but because the routine broke.

Boring trading looks the same every day. Same risk. Same rules. Same response to wins and losses. No improvisation.

If I feel excited, something is off. If I feel rushed, I stop. If I feel the urge to make something happen, I’m already done for the day.

This isn’t about removing personality. It’s about removing noise. The market provides enough uncertainty on its own.

Trading shouldn’t feel like a highlight reel. It should feel like work. Quiet, repetitive, sometimes dull work.

And that’s exactly why it works.