Tag Archive for: Strategy

Ask a room of traders whether they have an edge and nearly every hand goes up. Ask them to write it down in one sentence, in a form another trader could follow, and most stop.

That gap is the problem. “Edge” is one of the most used and least defined words in trading. It gets used to mean confidence, or experience, or a feeling that things are going well lately. None of those can be measured. If you cannot measure it, you cannot tell whether you have one.

So start with a definition that does some work.

What an edge actually is

An edge is a repeatable set of conditions under which your outcomes, over a large enough sample, are better than random after costs.

Three parts. All of them matter.

Repeatable. You can specify the conditions in advance, in writing, and someone else could read them, apply them to the same chart and reach the same decision. If the conditions only become clear after the move has happened, they are not conditions. They are hindsight.

Over a sample. Not three trades. Not a good week. A run of outcomes large enough that luck starts to wash out. Any set of rules, however arbitrary, will produce a winning streak somewhere.

After costs. Commissions, exchange fees and slippage. On futures, costs are small per contract and constant per trade, which makes them easy to ignore and quietly fatal to small edges. A setup that makes 0.05R per trade before costs can make nothing at all after them.

Slippage is the difference between the price you expected and the price you got. It shows up most on stops and in fast markets.

Write it in a form that could be proved wrong

Here is the practical test. Can you write your edge as a statement specific enough to be tested?

“I trade market structure” is not testable. Neither is “I buy at Points of Interest when the context lines up.” They describe an approach, not a rule. Two traders could read them and take entirely different trades.

This is testable:

When price sweeps the prior day high and closes back below it within two candles on the 15 minute chart, I short with a stop above the sweep high and a target at the prior day low.

You may disagree with that rule. The point is that you could hand it to another trader, they could apply it to the last six months of charts, and you would both agree on which trades qualified.

The specificity is the point. A statement that vague cannot be proved wrong, which means it also cannot be proved right. And a belief that cannot be tested is not an edge. It is a preference.

Preferences are not worthless. Plenty of good traders start with one. But a preference that has never been counted is a hypothesis you have been paying to hold.

How many trades before you know anything

Honestly: more than you want.

Thirty trades tells you close to nothing. A 60% win rate over thirty trades is well within what a coin flip produces by chance. One hundred starts to be suggestive. Even then, a positive result may be luck, particularly if the whole record rests on two or three outsized trades.

That is uncomfortable, and worth sitting with. If you take two trades a day, one hundred trades is about ten weeks. That is the timescale on which the question gets answered. Not this week.

The numbers worth recording

For each testable statement, record these:

  • Number of trades taken
  • Win rate
  • Average win in R
  • Average loss in R
  • Expectancy per trade in R
  • Largest drawdown in R
  • Net result after costs

R is your risk on the trade, expressed as one unit. If you risk $200 and make $400, that is +2R. Using R rather than dollars means the record still means something when your position size changes.

Expectancy is the number that matters most. It is the average result per trade in R: multiply your win rate by your average win, then subtract your loss rate multiplied by your average loss. A method that wins 40% of the time with an average win of +2R and an average loss of -1R has an expectancy of +0.2R per trade. Modest, and enough.

Expectancy survives account size changes. Net dollars do not. A trader who doubles size after a good month can post a bigger P&L while the edge underneath quietly gets worse.

Two ways traders break their own test

The first is curve-fitting. You look at the trades that lost, add a condition that would have excluded them, and repeat until the statement describes your past trades almost perfectly. What you have built is not a rule. It is a description of history. If a rule carries more than about four conditions, ask which ones you added after seeing the results.

The second is quieter and more common. You take fifteen trades, hit a losing run, decide the rule needs adjusting, and start again. Do that a few times and the sample never accumulates. You have been trading for two years and you still have no record of anything. Not because you were undisciplined, but because you kept restarting the clock.

Both come from the same place: wanting the answer to be yes.

What to do this week

Write one statement. Entry condition, stop placement, target, timeframe, and the market you will trade it in. Read it back and ask whether another trader could apply it without ringing you.

Then take that trade, and only that trade, for the next fifty occurrences. Log the seven numbers. Do not adjust the rule mid-sample. If you find a genuine flaw, note it, finish the sample anyway, and test the revision as a separate statement.

At the end you will have one of three answers. It works. It does not. Or the sample is too small to say and you need another fifty.

That third answer is the one most traders skip past, and it is a real result. Not knowing yet, with a record building underneath you, is a better position than being certain with nothing written down.
Two traders take the same course. Same rules, same instrument, same hours at the screen. Six months later one is flat and the other is down 30%.

The easy conclusion is that the strategy failed for one of them. It didn’t. They were never running the same strategy. They were running the same document.

A written strategy is a set of instructions. An executed strategy is what actually happened at the desk. Nearly all of the difference lives in the gap between them, and most traders never look, because they only ever examine the document.

Here is what really differs, in rough order of damage.

Two traders splitting their trading hours differently but using the same strategy are testing different things, then comparing results as if they were one.

The signals you skip are a strategy decision

Any strategy worth following produces more valid signals than one person will take. You are asleep, at work, or unconvinced. So you filter. Everybody filters.

The question is what your filter selects for.

One trader takes the clean setups and passes on the marginal ones. The level is obvious, the entry sits where the plan says it should. Dull. Dull is the point.

The other passes on the clean ones because they look slow, and takes the marginal ones because something is happening. Faster candles. A level that nearly holds. A move already underway.

Neither has broken a rule. Both would say they follow the strategy. But hand their filled orders to a stranger and they would be read as two different methods. One is taking a subset with better than average characteristics. The other is taking a subset selected for excitement.

Selection is the largest single variable, and it is invisible, because nobody logs the trades they didn’t take.

Size changes who you are by week three

Same rules, different risk per trade. Two $50,000 accounts. One trader risks 1%, or $500. The other risks 3%, or $1,500.

Now run six losses in a row, which any honest strategy hands you eventually. The first trader is down about 5.9%. Uncomfortable. The second is down about 16.7%. That isn’t uncomfortable, that is a different emotional state.

And it feeds back. The trader down 16.7% hesitates on the next valid signal, or sizes up to make it back. By week three they are not the trader who wrote the rules. Their sizing has quietly rewritten their selection and their exits.

Risk per trade gets discussed as an arithmetic question. It is a psychology question wearing an arithmetic costume.

The same setup at a different hour is a different setup

Volatility, volume and who is in the market change through the day. A setup taken in the first thirty minutes of the US session and the same setup taken in a quiet midday drift share a shape and little else.

Two traders splitting their trading hours differently but using the same strategy are testing different things, then comparing results as if they were one.

Taking +1R when the plan says +3R

Say the strategy wins 40% of the time and targets +3R. Over a hundred trades: 40 wins at 3R, 60 losses at 1R. That is 120R less 60R: +60R, or +0.6R per trade.

Now exit early. You take +1R when the trade stalls and the screen gets uncomfortable. Your win rate rises, because more trades reach +1R than reach +3R. Say it rises to 55%. That is 55 wins at 1R against 45 losses at 1R: +10R over a hundred trades, or +0.10R each.

Same entries. Same losses. A sixth of the return.

To get back to +0.6R while exiting at +1R, that trader would need to win 80% of the time, and nothing about their entry produces 80%. They have moved themselves to a point on the win rate and risk-reward curve their method cannot support, one sensible-feeling decision at a time.

A strategy followed 80% of the time is a different strategy

Fifty trades is a sequence, not just a sample

Two people run the same positive expectancy strategy for fifty trades. Same edge. Different order.

At a 40% win rate, six losses in a row has a probability of about 4.7% from any given starting point, so across fifty trades you should expect one. Whether it lands at trades 1 to 6 or trades 31 to 36 is luck.

The one who meets it first rarely reaches trade fifty. They adjust something at trade nine, and again at trade seventeen. By trade fifty they have run four strategies for twelve trades each and learnt nothing dependable about any of them.

A strategy followed 80% of the time is a different strategy

The 20% you deviate on is not a rounding error. It is a second, unnamed strategy with unknown properties, and its trades sit in the same account, so your results describe a blend you have never written down and cannot test.

None of this is a story about discipline as a personality trait. Some people are steadier than others, but that is not the useful part. The gap between the written strategy and the executed one can be measured, and measuring it doesn’t need a change of character. It needs a record.

What to log for the next two weeks

Every valid signal the strategy produced. Not just the ones you took.

Four fields for each:

  • Taken or skipped
  • If skipped, the reason, written at the time
  • Session and time of day
  • Risk taken, and where you exited versus the plan

By the end you will have two strategies on paper: the one in your Playbook, and the one you ran. Read the skip reasons together and the filter you didn’t know you had becomes obvious. Read the exits together and you will see your real risk-reward.

That log is the difference between the two traders, written down.

Most study time goes on the smaller half of the problem. Another confirmation tool, a tighter entry, a different instrument. The executed version, the one with the skipped signals and the early exits, is the version you are being paid or charged for.

Write both down. Then you can compare them.

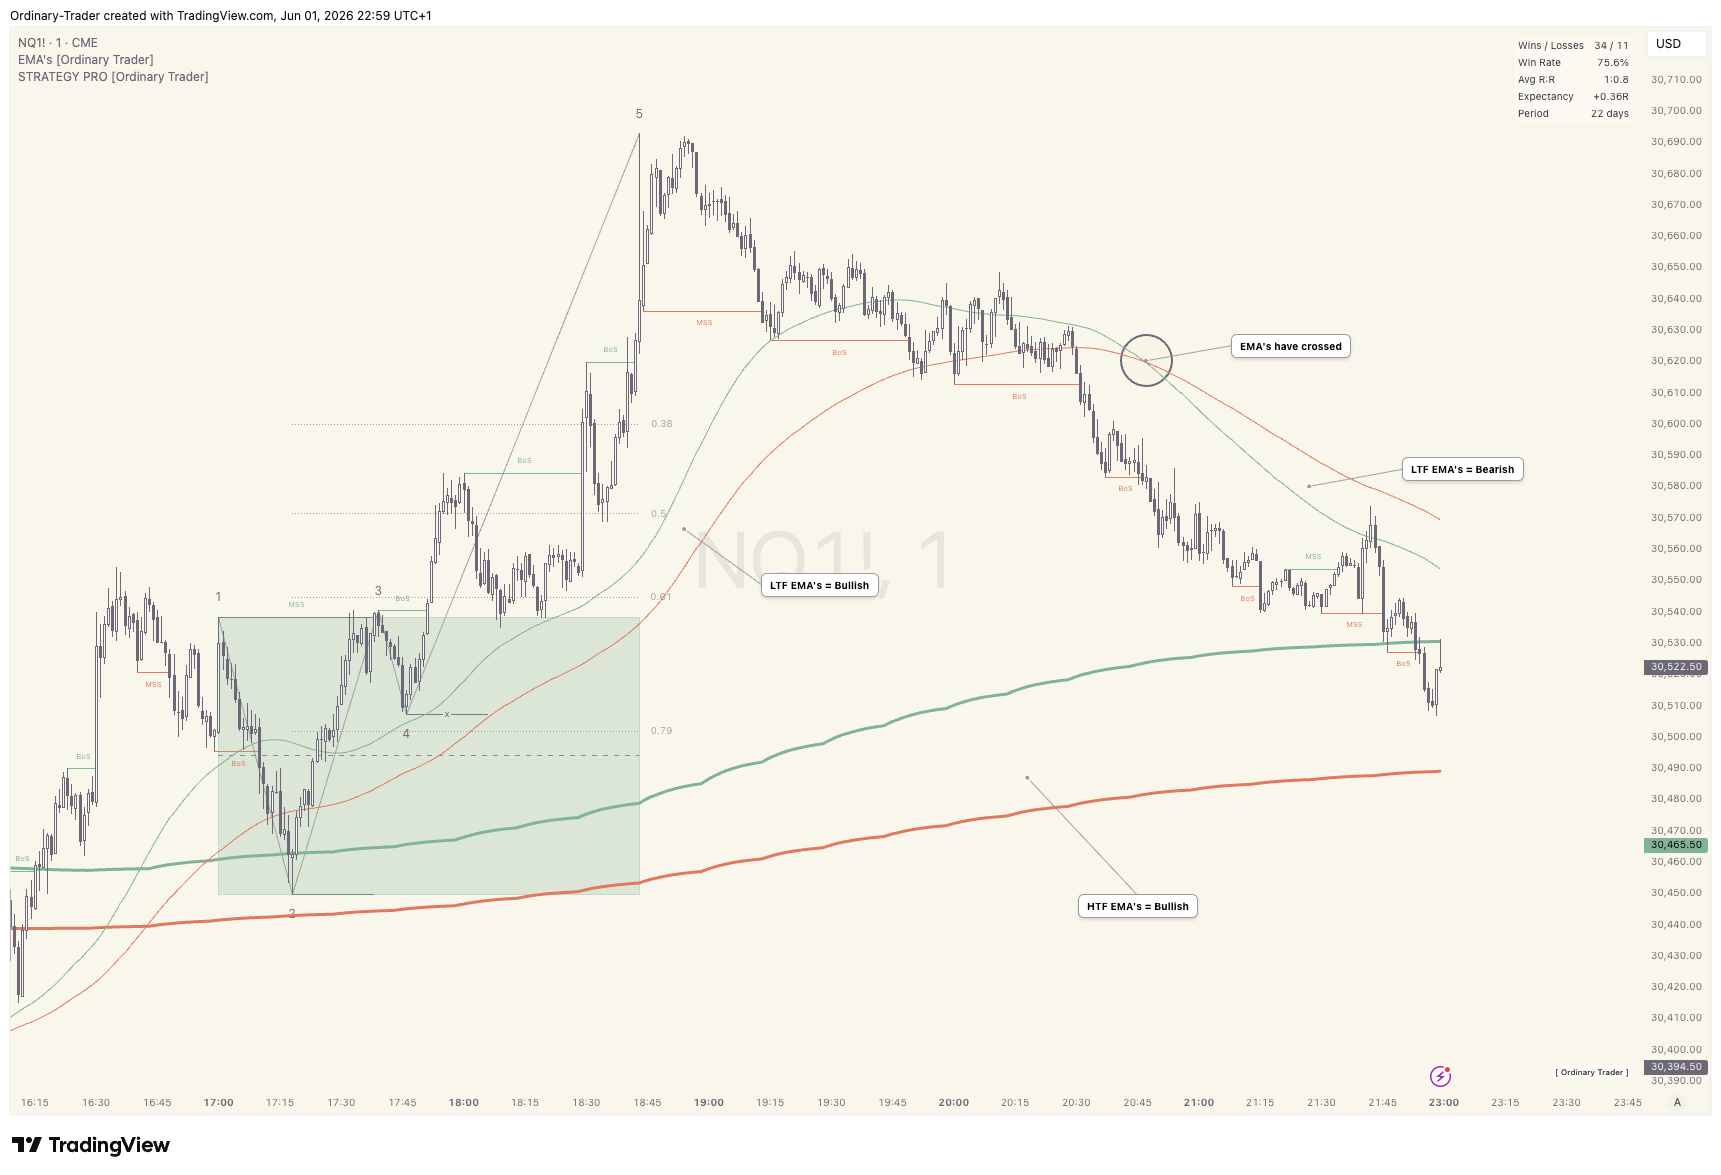
The STRATEGY indicator has two filters that both use EMAs to keep you trading with the trend, but they behave nothing alike. They serve very different purposes. That’s the part worth getting straight, because the shared “EMA” name does most of the confusing.

One checks where a Stage in the STRATEGY Sequence sits against a single moving average line. The other reads the broader, higher-timeframe trend from two moving averages and only reveals setups that align with the overall EMA direction. Both use EMAs as a building block, but they do completely different jobs.

Here’s what each one does, and when to reach for it.

(EMA is short for exponential moving average. It’s a line that follows price but gives more weight to recent candles, so it reacts faster than a plain average.)

LTF and HTF EMA’s working together

The EMA Filter: one level against one line

The EMA Filter asks a simple question. Where does a specific price level sit relative to a single EMA? If it’s on the wrong side, the setup gets thrown out.

You pick two things. A period (default 50) and a timeframe (default is whatever your chart is on). Then the Apply At setting decides which price level it checks, and at what point in the setup’s life:

  • Sequence Creation: the Step 1 break level, when the sequence first forms.
  • Liquidity: the Step 4 level, when liquidity confirms.
  • Sequence Completion: the Step 5 sweep level, after the sweep.
  • Flip Creation: the flip entry level, the moment the flip triggers.

For a bullish setup, that level has to be above the EMA. For a bearish one, below it.

Say you set Apply At to Flip Creation with the 50 EMA. You’re telling the indicator: only let me into a bullish trade if the flip pivot is above the 50 EMA at the moment it triggers. If it’s below, the setup gets discarded and labelled “EMA” on your chart, so you can see what it removed.

Two things people get wrong here.

First, it’s a one-time snapshot, not a running check. It looks once, at the stage you picked, and that’s it. If the setup passes and price later crosses back over the EMA, the setup stays valid. The filter has already done its job.

Second, “TF = Chart” does not mean the daily 50 EMA. It means whatever timeframe you’re looking at. On a 3 minute chart, it’s the 3 minute 50 EMA. If you want the daily as your reference, set the timeframe to D yourself.

One practical note to close this out. Flip Creation is the strictest option, because it checks right at entry. Sequence Creation is the loosest, because it checks early, before the setup has matured. That’s the trade-off. Filter harder and you cut more setups, including some that would have worked anyway.

The HTF Bias Filter: which way the bigger trend leans

This one works differently. Instead of one price level against one EMA, it looks at two EMAs on a higher timeframe and only allows setups in the direction those two are pointing.

You pick a higher timeframe (I suggest 15 min), a fast EMA (default 50) and a slow EMA (default 100). The rule is plain. Fast above slow means the higher-timeframe bias is bullish, so only bullish setups are allowed. Fast below slow means it’s bearish, so only bearish setups are allowed.

With the defaults, the indicator only reveals bull setups when the daily 50 EMA sits above the daily 100 EMA. If the 50 is below the 100, no bull setups appear on your chart at all. Not even the clean ones. Every other condition can line up and you’ll still see nothing.

There’s no Apply At option here, and that’s on purpose. The higher-timeframe cross is a regime check. It’s about the broader trend, which only matters when a setup first forms. Once a sequence has cleared that gate, the bias can shift later without touching the trade.

The EMA pair is a dial you can turn. Tighter pairs like 20/50 flip bias more often, so more setups but more whipsaws. Wider pairs like 100/300 are steadier, fewer setups but cleaner trend regimes.

Same tool, two different questions

If you only remember one thing, make it this. The EMA Filter compares a price level to one EMA. The HTF Bias Filter compares two EMAs to each other. One judges where your entry sits. The other judges what kind of trend you’re in.

EMA Filter HTF Bias Filter
What it compares A price level vs one EMA Two EMAs against each other
Timeframe Chart or HTF (your choice) Always HTF
When checked Step 1, 4, 5 or Flip (your choice) Always at sequence creation
Rejected setups Visible, labelled “EMA” Never appear at all
Best for Filtering setups by entry location Filtering by broader trend regime

That difference in purpose is the thing to hold on to. One is a precision tool for a single setup. The other is a broad gate for the whole session. They answer different questions, so they’re not really alternatives. They’re a pair.

Can you run both at once?

Yes, and they pair well. The HTF Bias Filter gives you the broad regime, the kind of trend you’re trading inside. The EMA Filter then refines individual setups within that trend, checking where the entry sits against a closer moving average.

Turn both on and the filters stack. A setup has to clear the higher-timeframe regime check and the price-level check before it earns a place on your chart. Stricter, fewer setups, but every one that survives has passed both questions.

Which is the point of a filter in the first place. It isn’t there to give you more trades. It’s there to quietly remove the ones that don’t fit, before you ever have to decide.

Trade well. Stay ordinary.